Robin Radar’s Possible €2 Billion Sale Points to a Counter-Drone Land Grab
Counter-UAS
Counter-uncrewed aerial systems refers to technologies used to detect, track, classify and defeat drones.
Sensor fusion
The process of combining inputs from radar, cameras, radio-frequency sensors and other sources to create a more reliable threat picture.
IDIQ contract
An indefinite-delivery, indefinite-quantity contract lets a government buy goods or services over time without setting exact quantities upfront.
System of systems
A defense architecture made of multiple connected components, such as sensors, command software, jammers and interceptors, working together.
€2B valuation
Robin Radar’s sale process could value the Dutch drone-detection company at about €2 billion.
Platform shift
Counter-UAS is moving from niche hardware buys toward integrated detection, classification, command and effector architectures.
Service model
Vendors are increasingly selling lifecycle support, software updates and training alongside counter-drone hardware.
BAE Systems’ reported exploration of a bid for Dutch drone-detection specialist Robin Radar Systems is less a one-off M&A story than a signal of where the counter-uncrewed aerial systems market is heading.
A sale process that could value Robin Radar at about €2 billion would place a once-specialized radar company in the same strategic category as electronic warfare, air defense and battlefield command-and-control — capabilities that large defense companies increasingly need to own, not merely integrate through partnerships.1
The attraction is clear. Small drones have moved from episodic battlefield nuisance to persistent military, homeland-security and infrastructure threat. That has elevated counter-UAS from a niche procurement line into a platform problem: how to detect, classify, prioritize and defeat cheap aerial threats at scale across military bases, borders, public events and critical infrastructure.
Market analysis now frames the sector as entering a consolidation phase, with larger defense and security groups acquiring or funding specialist technology rather than relying only on supplier relationships.2
Robin Radar sits at the front end of that chain. Founded around compact radar systems and later adapted for drone detection, the company represents the kind of sensing layer that primes want to control. It shapes everything downstream: track quality, classification confidence, the cueing of electronic-warfare or kinetic interceptors, and the data available for command systems.
Reuters reported through MarketScreener that BAE is among potential bidders exploring an offer. Private-equity firms including CVC, Blackstone, Advent and EQT have also been linked to interest in the business.1
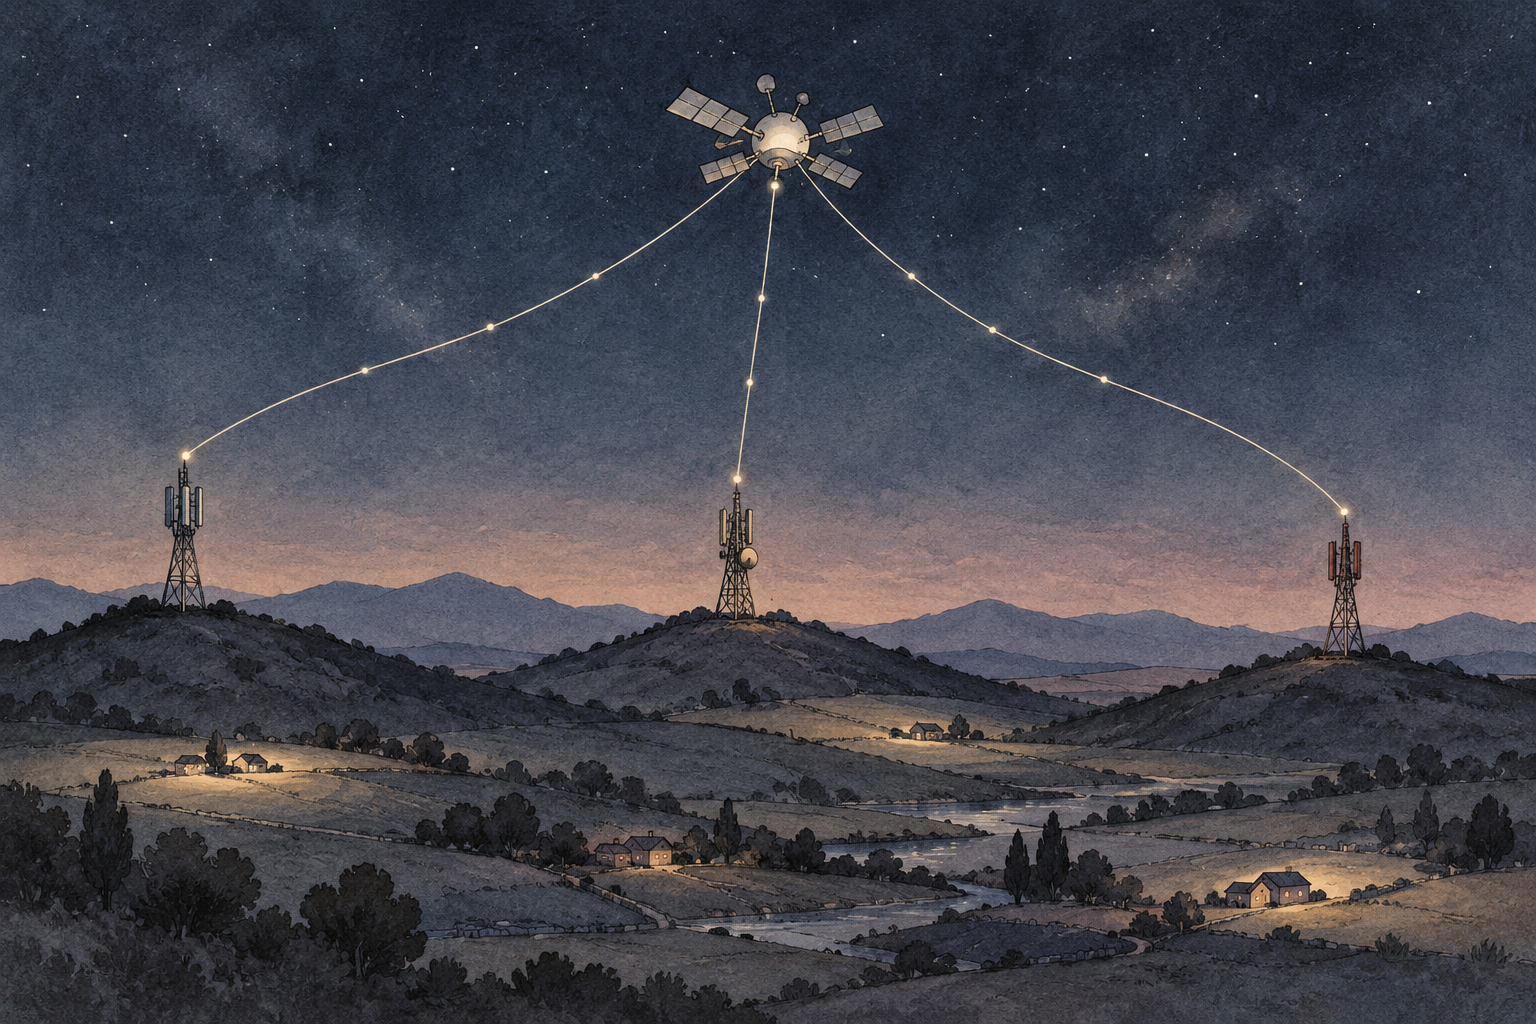
In counter-drone architectures, detection is no longer just a radar feed. The modern requirement is persistent sensing fused with electro-optical systems, radio-frequency detection, acoustic inputs, artificial-intelligence classification and a command layer that can recommend or authorize responses.
U.S. counter-UAS procurement is moving in that direction. Recent coverage of Joint Interagency Task Force 401 highlighted sensor-fusing systems that autonomously classify threats, operate on open architectures and are positioned for Domestic Shield demand.4
That shift changes the industrial logic. A prime contractor that owns a trusted detection layer can shape the rest of the system architecture. It can decide which effectors are integrated first, how software updates are delivered, how data is shared with allies and how future upgrades are priced.
A prime that merely partners for detection risks being reduced to an integrator of someone else’s core data stream.
That is why Robin Radar’s possible valuation matters. A roughly €2 billion price tag would imply that buyers are not valuing the business only on today’s radar shipments. They are pricing the strategic option to anchor a broader counter-UAS stack — from detection and classification to battle-management software and effectors — in a market where governments are moving from pilot projects to scaled deployment.1
The demand side is also changing. A reported Pentagon counter-UAS memo from Defense Secretary Pete Hegseth placed a 30-day clock on drone-defense approvals, underscoring policy pressure to break approval bottlenecks and accelerate fielding through mechanisms such as JIATF-401 and indefinite-delivery, indefinite-quantity contract vehicles.3
That matters because slow, bespoke procurement has historically favored demonstrations and niche systems. Faster approvals and standing contract frameworks favor vendors that can scale, support and continually upgrade deployed systems.
The U.S. examples are multiplying. Digital Force Technologies’ reported $500 million JIATF-401 counter-drone IDIQ award points to demand for systems that combine sensing, autonomous classification and open-architecture integration.4 Smart Shooter’s reported award of up to $150 million for SMASH counter-UAS fire-control systems adds another layer: tactical defeat mechanisms are being scaled through the same government-backed framework approach.9
For defense primes, these vehicles create a strategic imperative. If counter-UAS becomes a recurring program category rather than a patchwork of urgent buys, ownership of key subsystems can determine who controls upgrades, sustainment revenue and future architecture standards.
For private equity, the same shift creates a buy-and-build opportunity: acquire specialist companies, professionalize delivery, add service revenue and sell into primes or public markets once the category matures.
The operational challenge is that no single technology solves the drone threat. Small drones vary in size, speed, autonomy, signature and communications link. Some are commercial quadcopters; others are one-way attack systems, loitering munitions or swarming platforms.
That pushes militaries toward layered architectures: radar and passive sensors for detection, software for classification and prioritization, jammers and cyber tools for soft kill, and guns, missiles, lasers or microwave systems for hard kill.
Recent Army experimentation illustrates the direction. The Jailbreak drill brought a high-power microwave drone-kill system into an environment focused on integrating sensors, command networks and effectors from multiple vendors.5 Leonardo’s testing of a land version of its 40mm naval gun similarly shows how major defense companies are adapting existing weapons into counter-drone layers rather than treating C-UAS as a standalone add-on.6
Other suppliers are working the same convergence from different points in the stack. IG Defence’s JWALA effort pairs low-cost solid-rocket interceptors with artificial-intelligence battle-management software, showing how hard-kill systems increasingly depend on digital command layers and sensor cueing to be effective.7
The result is a market where value migrates from individual pieces of hardware to the architecture that coordinates them.
Partnerships remain essential because counter-UAS requires many technologies. But the most important layers are becoming too strategic for primes to leave outside their balance sheets.
Detection data is the foundation for operational trust. Classification algorithms improve with use. Open architectures can become de facto standards. Sustainment contracts can run for years. These are not commodity inputs.
That explains why a company such as BAE would examine whether to acquire a specialist rather than simply integrate one. BAE already has positions in electronic warfare, military electronics and command systems. Adding a specialized small-drone detection business could strengthen its ability to offer end-to-end counter-UAS packages and deepen synergies with electronic-warfare portfolios.1
It also explains the private-equity interest. Financial sponsors can see that counter-drone companies are moving from experimental hardware suppliers into recurring defense-technology platforms. As procurement matures, buyers will pay for readiness, software updates, training, lifecycle support and rapid integration of new threat libraries.
DroneShield’s launch of Mission Ready Services highlights that transition toward lifecycle support, operator training, software updates and subscription-like service models in counter-drone deployments.8
The Robin Radar process also carries a European industrial-policy dimension. Defense dealmaking is under closer scrutiny as governments seek control over critical data, cloud, sensor and security infrastructure.
In the Reuters report, Parcom, Robin Radar’s owner, was described as preferring a European strategic or private-equity investor that could develop the technology for Europe’s benefit.1
That matters because counter-UAS systems generate sensitive operational data: where drones are detected, what facilities are protected, how defenses respond and where vulnerabilities remain. For European governments trying to strengthen defense autonomy, the nationality and governance of companies controlling those data layers can become as important as hardware performance.
The same logic favors consolidation within trusted blocs. A European prime acquiring a European detection specialist can promise customers a more sovereign architecture. A U.S. buyer may offer scale and capital but face greater political scrutiny. A private-equity owner may need to demonstrate that it will preserve sensitive capabilities, invest in domestic production and avoid fragmenting intellectual property across jurisdictions.
The next phase of counter-UAS consolidation is likely to focus on companies that control one of four layers: detection, classification software, command-and-control integration or low-cost effectors.
Detection specialists such as Robin Radar are especially attractive because they sit closest to the first decision point in the kill chain. If the system cannot find and classify the drone, the rest of the defensive stack is less useful.
That does not mean every specialist will be acquired by a prime. Some may remain independent architecture providers, some may pursue service models, and others may be rolled up by private equity before a later sale.
But the direction is becoming clearer: counter-drone capability is maturing from urgent-response hardware procurement into an enduring defense platform category.
For BAE and its peers, the question is not simply whether Robin Radar is worth €2 billion. It is whether counter-UAS detection will become a must-own layer of future air-defense, base-protection and homeland-security architectures. If the answer is yes, the cost of waiting may rise faster than the price of buying.
Comments