Gold’s rally is turning into a fiscal-risk trade
Real yield
A bond yield adjusted for expected inflation. Higher real yields usually hurt gold because bullion pays no income.
OAT-Bund spread
The yield gap between French and German 10-year government bonds. A wider spread signals a higher perceived risk premium on French debt.
Term premium
The extra return investors demand to hold longer-term bonds instead of repeatedly rolling short-term debt.
Safe-haven demand
Buying of assets perceived as protective during market stress, policy uncertainty or financial-system risk.
Gold gains
Spot gold rose 0.7% to $4,168.33 an ounce on October 6 as the dollar and Treasury yields eased.
Real yields
The 10-year TIPS real yield stood at 2.91% on October 6, underscoring gold’s resilience despite a high opportunity cost.
France risk
France’s 10-year OAT-Bund spread was 127.4 basis points on October 6, reflecting a persistent sovereign-risk premium.
Gold’s October 6 advance was not just another response to a weaker dollar or a modest pullback in Treasury yields. It signaled that bullion is increasingly being priced as insurance against sovereign-credit and market-liquidity risk — a shift from the usual playbook, in which gold rises when Federal Reserve rate expectations fall and struggles when real yields are high.
Spot gold gained 0.7% to $4,168.33 an ounce on Tuesday, while December futures settled 0.7% higher at $4,187.10, Reuters reported. The immediate catalysts were familiar: the dollar eased from a one-year high, and the U.S. 10-year Treasury yield slipped after reaching a more than two-decade high the prior day.1 But the more important detail was the source of demand. Reuters cited safe-haven buying tied to turmoil in French bonds and growing concern about U.S. Treasury markets.1
That combination matters for multi-asset investors. Gold is holding firm despite a U.S. 10-year par yield of 5.27%, a 30-year yield of 5.64% and a 10-year TIPS real yield of 2.91% on October 6 — levels that would normally impose a heavy opportunity cost on a non-yielding asset.8 Bullion’s ability to stay above $4,100 suggests investors are not simply buying a lower-rate story. They are paying for an asset outside the sovereign-liability complex.
The conventional model has not disappeared. Gold pays no coupon, so rising nominal and real yields increase the relative appeal of cash and bonds. Investing.com’s October 6 analysis captured the tension: falling odds of an October Fed hike should theoretically support gold, but elevated longer-dated Treasury yields and a still-firm dollar were preventing a clean breakout near $4,200.6
That is what makes the current price action notable. The market was pricing only about a 22% chance of an October Fed hike, but still roughly an 84% to 85% probability of at least one increase by December, according to Reuters reports citing CME FedWatch data.12 In other words, the Fed impulse was less hawkish at the front end, but not clearly dovish across the full path. At the same time, longer maturities remained pressured by forces beyond the next policy meeting: inflation risk, bond supply, fiscal deficits and term premium.
That distinction is now central to the gold thesis. If the Fed were the only variable, gold’s behavior would be easier to read: weaker labor data and lower near-term hike odds would lift bullion; higher yields would cap it. Instead, gold is responding to a broader question: whether the world’s benchmark sovereign-bond markets still offer enough liquidity, credibility and diversification as fiscal paths deteriorate.
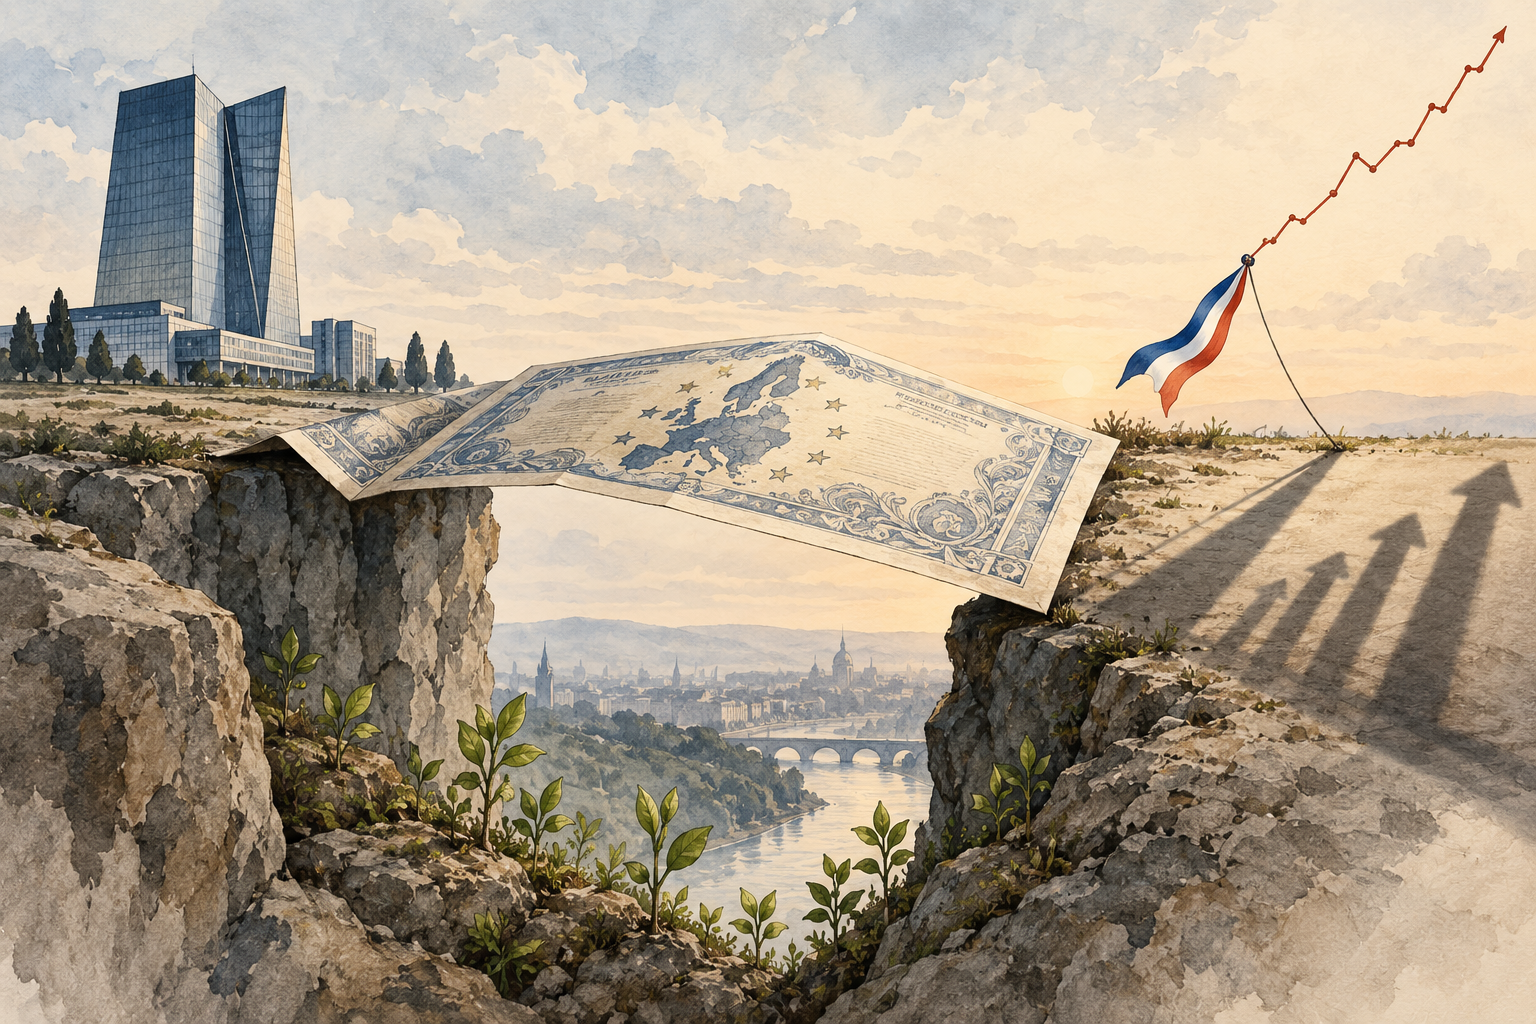
The French bond market provided the clearest sovereign-risk catalyst. The euro rebounded on October 6 after falling to its lowest level in 17 months the day before, as a rally in French government bonds eased some immediate concern about eurozone debt stress.2 But the relief was partial. French debt had been hit as politicians struggled to contain the budget deficit ahead of the 2027 election, and Reuters noted that global bond markets had been battered by expectations for central-bank tightening and concern about high borrowing.2
Market pricing still showed a large risk premium. The French 10-year OAT yielded 4.72% on October 6, versus 3.45% for the German Bund, leaving the OAT-Bund spread at 127.4 basis points, according to Ideal Investisseur data sourced to Banque de France and Deutsche Bundesbank.10 That spread had narrowed by 16 basis points from the previous session, but it remained well above its one-year average of 75.3 basis points.10
The political backdrop explains why gold investors are paying attention. Le Monde reported that France’s 2027 draft budget failed to reassure either lawmakers or creditors, with markets skeptical that the plan could pass a deeply divided National Assembly.3 The article said French rates jumped to nearly 5%, the OAT-Bund spread rose above 1.5 percentage points, and public debt exceeded 119% of GDP.3 Even if those peak stress levels eased by October 6, the message for portfolios was clear: fiscal politics can quickly become a market event.
Gold’s relevance in that environment is not that France alone drives bullion. It is that France is a developed-market example of a broader problem: investors are demanding more compensation to hold sovereign debt just as governments need to issue more of it. When the asset class traditionally used as a safe harbor begins to trade with greater fiscal-risk sensitivity, gold’s lack of issuer liability becomes more valuable.
The U.S. side of the trade is subtler but arguably more important. Reuters’ gold report explicitly paired French bond turmoil with concern about U.S. Treasury markets as a source of safe-haven demand.1 That framing matters because Treasuries are typically the safe asset against which other risks are measured. When investors hedge the market structure around Treasuries themselves — debt supply, auction digestion, fiscal trajectory and liquidity — gold becomes a hedge against the plumbing of the system, not just inflation or recession.
The October 6 cross-asset backdrop reinforced that point. U.S. stocks rose, with the S&P 500 up 0.6% to a record and the Nasdaq adding 0.4% to its own high, helped in part by easing bond yields, according to the Associated Press.4 This was not a classic risk-off day. Gold rose alongside equities, not because investors were fleeing all risk, but because they were selectively hedging the macro foundation under risk assets: sovereign rates and the dollar.
GoldPrice.com showed spot gold around $4,130.58 early on October 7, down 0.62% from the last LBMA PM fix but still firmly above $4,100 after the prior session’s rally.12 That resilience is the point. Bullion is not breaking free of rate gravity, but it is refusing to behave as if real yields are the only variable that matters.
For asset allocators, the key implication is that gold’s correlation regime may be shifting. In a narrow Fed-cycle framework, gold competes with TIPS and cash. In a fiscal-credibility framework, it competes with confidence in sovereign duration, reserve currencies and market liquidity.
That does not make bullion a one-way trade. If Treasury yields fall because inflation cools and fiscal concerns recede, gold may rally on lower opportunity cost. If yields rise because real growth improves and risk appetite broadens, gold may lag. The more complicated scenario — and the one markets are now testing — is when yields stay high because investors demand more compensation for fiscal and liquidity risk. In that case, high yields do not necessarily undermine gold; they may help explain why hedging demand persists.
The portfolio question is therefore less about whether gold is “expensive” near $4,100 to $4,200 and more about what risk it is pricing. On October 6, the answer appeared to be less about the next Fed meeting and more about sovereign-debt credibility. That makes gold a barometer of investor trust in fiscal policy and bond-market depth — and a hedge against the uncomfortable possibility that the safest assets are themselves becoming sources of volatility.
Comments