UK autos face EU price for softer line on Chinese EVs
Made in Europe rules
Proposed EU industrial-policy rules that would prioritise European-made goods in public procurement and support schemes, especially in strategic sectors.
Countervailing duties
Tariffs imposed to offset subsidies that an importing authority says give foreign producers an unfair advantage.
Rules of origin
Trade rules used to determine where a product is deemed to be made, which affects tariff treatment and eligibility for support programmes.
EU pressure
Brussels reportedly wants the UK to raise tariffs on Chinese cars to avoid barriers under proposed “Made in Europe” rules.
Supplier risk
UK-listed suppliers such as Johnson Matthey are exposed to whether UK-made content remains eligible for EU-backed regional supply chains.
China surge
Chinese brands reportedly hold more than 15% of the UK new-car market, increasing EU concern over tariff circumvention.
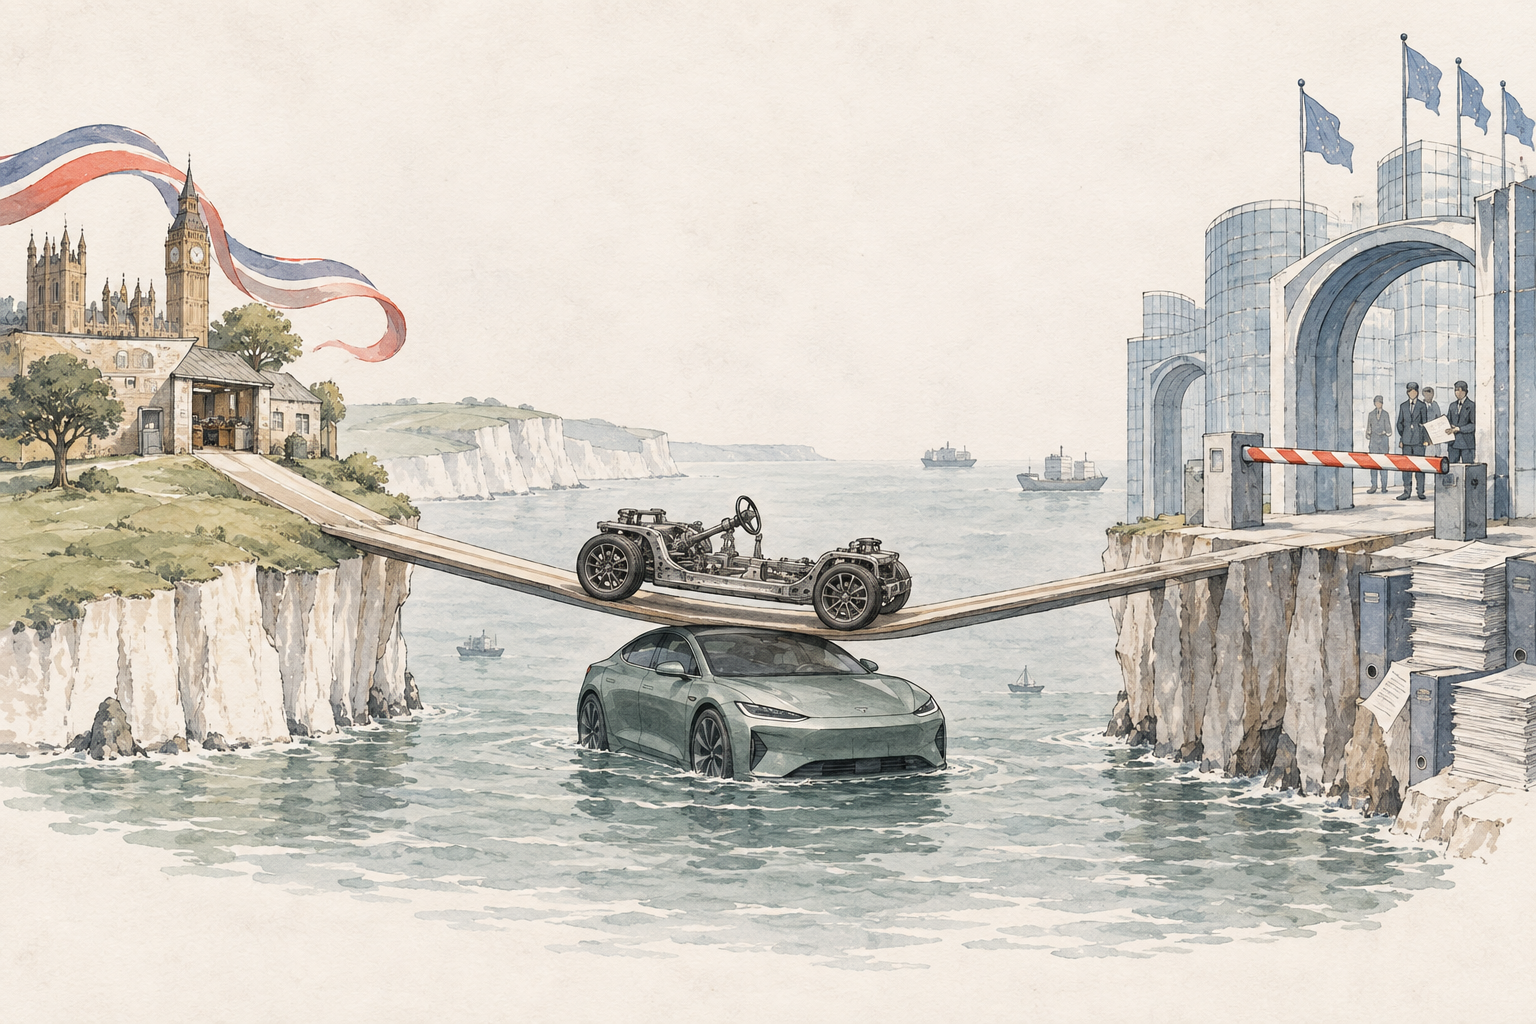
Brussels’ reported demand that the UK raise tariffs on Chinese cars puts a market price on Britain’s attempt to keep a looser China trade stance while preserving privileged access to European industrial policy.
For UK equity and policy investors, the issue is no longer only whether cheap Chinese EVs pressure domestic manufacturers. It is whether refusing to mirror EU trade defences could leave British-made cars, parts, batteries and industrial inputs outside the bloc’s emerging “Made in Europe” support architecture.2
Reuters, citing the Financial Times, reported that Brussels told Prime Minister Andy Burnham’s government Britain should increase tariffs on Chinese cars and align more closely with EU trade policy to avoid barriers on key exports under proposed European-content rules.2 The EU’s concern is twofold: Chinese vehicles could use the UK as a lower-tariff route into Europe, and UK-based production could gain unfair access to EU procurement or subsidy schemes while Britain keeps a more open import regime.3
That creates a direct tension for UK-listed autos and industrial suppliers. Companies with UK manufacturing footprints and European customers benefit from frictionless regional supply chains. Some also benefit from lower-cost Chinese inputs, Chinese investment or a UK market where Chinese brands can expand faster than in tariff-protected EU channels.
Johnson Matthey is the cleanest listed read-across in the supplied equity set. The UK group’s emissions-control, platinum-group metals and hydrogen businesses sit in the advanced-materials supply chain that could gain from regionalisation. They also depend on stable cross-border demand rather than a fragmented UK-EU policy split.6
The immediate policy problem is that the EU has already moved further than the UK against Chinese electric vehicles. IndexBox’s summary of the FT-reported dispute notes that the European Commission secured backing in late 2024 for additional duties on China-made EVs ranging from 7.8% to 35.3%, while Britain has been reluctant to import that position wholesale.3 SINGULISM reports that the UK still applies the 10% most-favoured-nation car tariff and has not added EU-style anti-subsidy duties.1
For Brussels, that gap is not a technicality. If the EU is building industrial rules that favour European-made vehicles, batteries, chemicals and components, a UK that remains open to China risks being treated as a back door rather than a partner.
Reuters’ syndicated report said an EU official argued that a customs union would solve much of the “Made in Europe” problem and the tariff-difference issue, because Brussels fears Chinese cars could avoid EU duties by routing through the UK.2
The UK’s official line remains independence. A government spokesperson said trade measures are set independently and according to the UK’s economic and industrial interests, while also stressing the need to protect UK-EU trade flows.4 That is the bind: independence has value only if it does not reduce access to the UK’s most important industrial market.
The most exposed listed names are not necessarily finished-vehicle importers. They are suppliers whose valuations depend on regional production volumes, emissions technology, hydrogen components, battery materials, metal processing, testing and engineering demand.
Simply Wall St’s investor screen linked the tariff debate to Johnson Matthey, EBRO EV Motors and Gränges, arguing that protectionism, subsidies and export checks could reshape supply chains and pricing power.6
For Johnson Matthey, the issue is less “Chinese EV tariff winner” than “regional supply-chain optionality.” Its clean air catalyst business remains tied to hybrid and heavy-duty emissions regulation, while its hydrogen and advanced-materials activities could benefit if the UK and EU steer public support toward regional suppliers.6 But that upside weakens if UK-made content is excluded from EU procurement or subsidy frameworks because London refuses to align on China tariffs.
For UK exporters more broadly, the danger is a gradual discount on UK industrial assets. A plant that can sell into the EU, qualify for European support and source competitively has strategic value. A plant that must choose between Chinese-linked inputs and EU eligibility has less.
This matters for autos because SINGULISM cites roughly €80 billion of annual UK-EU automotive trade and notes that the EU remains the largest export market for UK vehicle production.1
The EU pressure is arriving because Chinese EV momentum is no longer theoretical. SINGULISM reports that Chinese brands account for more than 15% of the UK new-car market, with about 223,000 Chinese-brand registrations from January to August 2026 and a dealer footprint that rose from 95 outlets in May 2024 to 440 in May 2026.1
BYD, Chery-linked Jaecoo, SAIC-owned MG, Geely and Leapmotor are no longer peripheral entrants. They are becoming part of the UK retail landscape.1
That makes the UK attractive to Chinese automakers: it is large, EV-receptive and less tariff-restrictive than the EU. AION’s UK launch strategy, reported by Forbes and syndicated by Yahoo Autos, points to continued Chinese brand expansion even as the EU tightens its stance.9
From a consumer and dealer perspective, lower tariffs support choice and pricing. From Brussels’ perspective, the same openness undermines the credibility of European industrial defences.
The broader European market context strengthens Brussels’ hand. WebProNews, citing ICCT and ACEA figures, reported that battery-electric cars reached about 29% of European August registrations and 21.7% of EU registrations over the first eight months, matching petrol’s share. Chinese groups including BYD, Chery and Leapmotor were reported to have sold between two and three times more than last year in some tallies, while Geely and SAIC also gained share.7
The EU is therefore responding to a live competitive shift, not a hypothetical future threat.
The proposed “Made in Europe” framework changes the bargaining dynamic. It is not merely a tariff wall; it is a demand-shaping policy.
SINGULISM describes the EU’s Industrial Accelerator Act as an attempt to use public procurement and public support in sectors such as autos, steel and batteries to favour European-made and low-carbon goods, noting that EU public procurement exceeds €2 trillion annually.1
That is why UK access matters. If British products qualify as trusted or European-adjacent, UK suppliers can remain embedded in EU decarbonisation, vehicle and battery investment cycles. If they do not, the UK risks becoming a peripheral manufacturing base: close to Europe geographically, but outside the rules that determine which plants and suppliers receive demand support.
The UK wants the best of both worlds: attract Chinese EV investment, keep consumer prices low, preserve manufacturing jobs and avoid exclusion from EU schemes. But the EU appears to be turning those goals into a sequence: first alignment, then access.
A rapid UK move to EU-style tariffs would carry costs. Memesita’s report, citing Chinese expert reaction, framed the EU’s pressure as likely to raise business costs and disrupt supply chains, while warning that full decoupling is unrealistic given embedded industrial links.5
That matters for the UK because its industrial strategy has leaned on foreign investment as much as protection. Chinese automakers are not just import competitors. They are prospective R&D partners, plant-utilisation partners and local employers.
SINGULISM points to Chery’s planned R&D base at UTAC Millbrook and its non-binding talks with Nissan to explore producing passenger cars for the UK market at Sunderland.1 Those developments show why a simple “raise tariffs to protect domestic autos” policy is harder in Britain than in Brussels. Tariffs could protect incumbents, but they could also reduce the incentive for Chinese groups to localise activity in the UK.
For UK equity investors, the next catalyst is not only whether the UK raises duties on Chinese cars. It is whether Brussels defines UK-made goods as eligible for “Made in Europe” treatment, and on what conditions.
A narrow deal that protects autos, batteries, chemicals or energy-intensive goods could support UK suppliers. A hard exclusion would increase the risk premium on companies dependent on EU customers or European policy demand.
The practical watchlist is clear. First, any UK signal on anti-subsidy duties or safeguards against China-made EVs. Second, the treatment of UK content under EU procurement and subsidy rules. Third, rules of origin for Chinese-invested UK production. Fourth, corporate responses from UK-listed suppliers, especially those selling into emissions control, hydrogen, battery materials and industrial metals markets.
The UK’s post-Brexit flexibility was supposed to let it move faster than the EU. In autos, that flexibility now has an opportunity cost. If Britain keeps its China tariff stance softer than Brussels’, domestic manufacturers may find that the price is paid not at the border, but in lost eligibility for the European industrial programmes that increasingly shape where capital is deployed.


Comments