Claude for Financial Advisors tests connector-first AI for regulated wealth management
Model Context Protocol (MCP)
An integration framework for connecting AI models to external tools, data sources and workflows through structured interfaces.
Registered Investment Adviser (RIA)
A firm or individual registered to provide investment advice, typically subject to fiduciary and compliance obligations.
Custodian infrastructure
Systems operated by financial custodians that hold client account records, assets and transaction data.
Human-in-the-loop approval
A control pattern in which AI can assist with analysis or drafting, but a responsible professional must approve consequential or client-facing actions.
Agentic workflows
Claude for Financial Advisors targets meeting prep, follow-ups, portfolio review and compliance-oriented checks for wealth advisers.
Partner network
Launch coverage names major wealth platforms including Schwab, Vanguard, BlackRock, Orion, Addepar, Envestnet and iCapital.
Data boundary
The architecture relies on partner systems and MCP-based connectors while keeping client records on custodian or wealth-tech infrastructure.
Anthropic has launched Claude for Financial Advisors, a wealth-management version of its AI assistant designed to help advisers prepare for meetings, draft follow-ups, review portfolios and run compliance-oriented checks without moving client records into Anthropic-controlled systems.1
The product matters beyond wealth management because it offers a concrete architecture for regulated AI deployment. Claude queries client and portfolio information through partner platforms and Model Context Protocol, or MCP, connectors. Data remains on custodian or wealth-tech infrastructure, and advisers must approve regulated or client-facing actions before they are sent.4
For enterprise AI teams in banking, insurance, health care and other sensitive sectors, the launch is a test case for whether agentic systems can become useful without becoming new systems of record.
Anthropic is positioning the product around four adviser workflows: meeting preparation, follow-up communication, portfolio review and compliance checks.1 The company and launch coverage point to integrations across major wealth-management vendors, including Schwab, Vanguard, BlackRock, Orion, Addepar, Envestnet, iCapital, Wealthbox, Wealth.com and Zocks.3
Schwab’s role is especially significant because its platform reaches more than 16,000 registered investment adviser firms, giving the rollout a distribution path into the independent RIA market rather than limiting it to a narrow pilot group.1
The core design choice is not that Claude can summarize notes or draft emails. Those capabilities are already common across general-purpose AI assistants. The more consequential design is the data boundary.
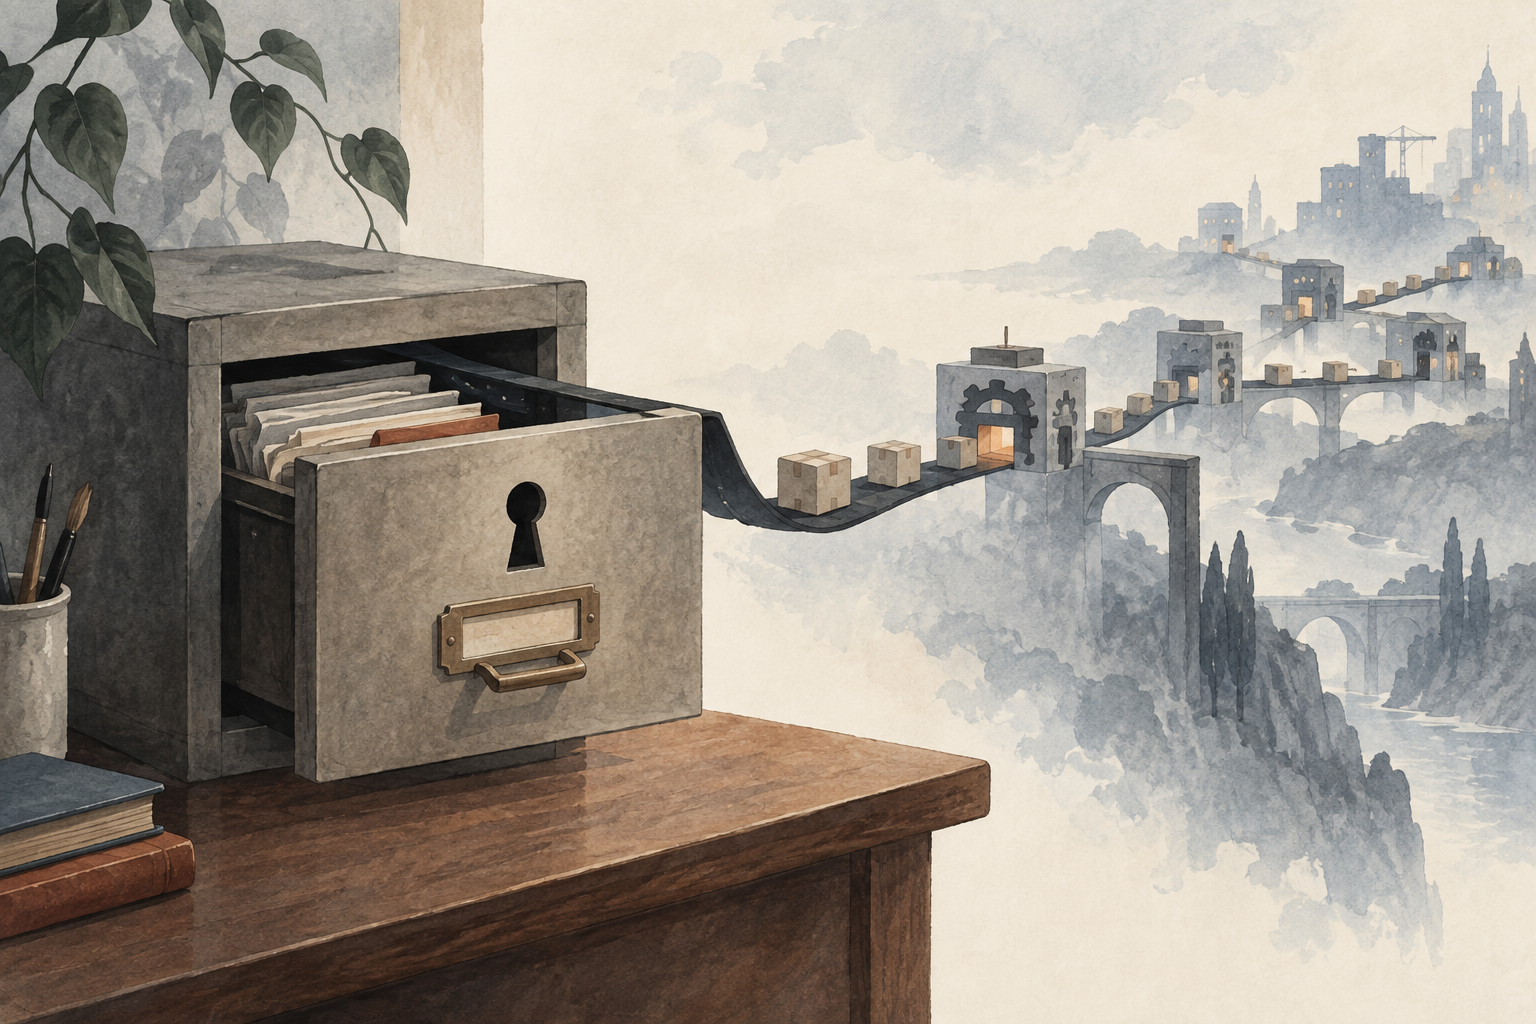
According to launch reporting, Claude for Financial Advisors uses MCP-based connections and partner-system integrations so client records remain on custodian or platform servers while Claude accesses the information needed for a specific task.4 In practice, this resembles a hub-and-spoke model: the AI assistant sits at the workflow layer, while account data, portfolio holdings, CRM records, planning information and meeting transcripts remain in specialized systems.
That is different from asking advisers to upload sensitive PDFs, spreadsheets or CRM exports into a general chatbot. It also differs from rebuilding a full wealth-management data lake under the AI vendor. Instead, Anthropic is trying to make Claude useful through controlled retrieval and action pathways into systems advisers already use.
For regulated-industry technologists, that pattern is important. If MCP-style connectors mature, vertical AI agents may not need to own regulated records directly. They can request context, perform reasoning or drafting, and return outputs subject to policy, permissions and human approval. That could lower adoption barriers in sectors where data residency, vendor-risk management and auditability often slow AI deployments.
The product is also framed around adviser approval before client-facing or regulated activity occurs.1 That approval layer is not cosmetic. In wealth management, recommendations, portfolio changes and client communications can implicate fiduciary duties, suitability standards, disclosure obligations and firm supervision rules.
A connector-based architecture can reduce the need to copy data, but it does not eliminate responsibility for the output. If Claude drafts a recommendation after retrieving portfolio holdings and client objectives, the adviser and the firm still need to evaluate whether the recommendation is appropriate, documented and compliant.
The requirement that advisers approve client-facing actions keeps the AI in an assistive role rather than making it an autonomous adviser.4
This is likely to be a recurring pattern for enterprise agents in regulated environments. The near-term value is not full automation of regulated judgment. It is compressing preparation, retrieval, drafting and review work while preserving accountable human sign-off.
InvestmentNews coverage of the rollout emphasized Anthropic’s Enterprise plan, data privacy controls and audit logs as central to adviser adoption.2 That emphasis reflects how financial firms evaluate AI tools. Accuracy matters, but so do retention settings, permissioning, audit trails, data-use commitments, administrative controls and integration with existing supervision processes.
For an RIA, broker-dealer or custodian, the question is not simply whether Claude can generate a polished meeting brief. The question is whether a firm can show what data was accessed, which user initiated the task, what output was generated, whether it was changed, who approved it and how the interaction fits the firm’s recordkeeping and compliance program.
That makes auditability a competitive requirement for vertical AI. In consumer AI, a useful answer may be enough. In regulated enterprise AI, a useful answer without traceability can be a liability.
Keeping data on custodian infrastructure reduces the risk of creating another large repository of sensitive financial records. But connectors introduce their own security and governance challenges.
The first is authorization. If Claude can query multiple systems, firms need fine-grained controls over which adviser, assistant, operations employee or supervisor can access specific accounts, documents and workflows. Enterprise AI agents must inherit or enforce existing entitlements rather than flatten them.
The second is data minimization. A meeting-prep workflow may need recent account activity, planning goals and prior notes, but not every document in a client file. Connector architecture is strongest when it retrieves the minimum context required for a task and logs that access.
The third is prompt and tool security. Agents that retrieve data and call tools are exposed to risks such as malicious instructions embedded in documents, CRM notes or external content. In wealth management, a compromised workflow could generate misleading summaries, surface inappropriate recommendations or attempt unauthorized follow-up actions.
The fourth is output governance. Even if input data remains in partner systems, generated text may contain sensitive information. Firms will need policies for where AI-generated meeting notes, draft emails and portfolio summaries are stored, retained and supervised.
Wealth management is a practical test market for this model because adviser work is information-heavy, repetitive and highly relationship-driven. Advisers spend significant time synthesizing client history, portfolio data, market context and planning details before meetings. They also produce follow-up messages, internal notes and compliance documentation afterward.
That creates a strong productivity case for AI. But the same workflows involve sensitive personal and financial information, making them difficult to automate with generic tools. The Paypers described the product as spanning integrations with major financial and wealth-technology platforms, underscoring that the value proposition depends on connecting Claude to the adviser’s existing operating environment rather than replacing it.3
ThinkAdvisor’s coverage placed the launch in the broader context of AI’s potential role in wealth management, where firms are trying to balance efficiency gains with adviser trust and client protections.5 That balance will determine whether tools like Claude become daily infrastructure or remain limited to controlled pilots.
Claude for Financial Advisors is part of a broader shift from chatbots to domain agents. The distinction is architectural. A chatbot answers from what the user types or uploads. A domain agent operates across approved tools, systems and workflows. In regulated industries, that shift is only acceptable if the agent can be constrained, monitored and audited.
MCP-style connectors are one candidate mechanism for that shift. They can standardize how models access tools and data sources, potentially making integrations more reusable and governable. But their success will depend on implementation details: permission boundaries, logging, consent, data retention, failure modes, security testing and clear responsibility among model vendors, platform partners and regulated firms.
Anthropic’s wealth-adviser launch does not prove that agentic AI is ready to operate independently in regulated industries. It suggests a more modest and plausible path: keep authoritative records where they already are, let the model retrieve context through governed connectors, use enterprise controls to monitor activity, and require licensed professionals to approve consequential actions.
If that pattern works in wealth management, it could become a template for vertical AI in other regulated sectors. If it fails, the likely reason will not be that advisers dislike automation. It will be that firms cannot get comfortable with the control surface around connected agents.
The launch therefore turns Claude for Financial Advisors into a live test of whether AI vendors can make agents useful without asking regulated enterprises to surrender control of their most sensitive data.


Comments