China’s Fuel-Export Restart Eases the Squeeze, but Not the Energy Shock
Crack spread
The margin between crude-oil input costs and the wholesale value of refined products such as gasoline, diesel and jet fuel.
Middle distillates
A category of refined products that includes diesel and jet fuel, both critical for freight and aviation.
3:2:1 crack spread
A common refinery-margin proxy that assumes three barrels of crude produce two barrels of gasoline and one barrel of distillate.
Golden Week
A major Chinese holiday period that can temporarily slow trade activity, logistics and administrative approvals.
Reuters via Yahoo Finance
news
China to resume October fuel exports after a brief halt, four trade sources say
Federal Reserve Bank of Dallas
other
Refinery outages pumping up fuel prices more than cost of crude oil
U.S. Energy Information Administration
government
Daily Prices
Exports restart
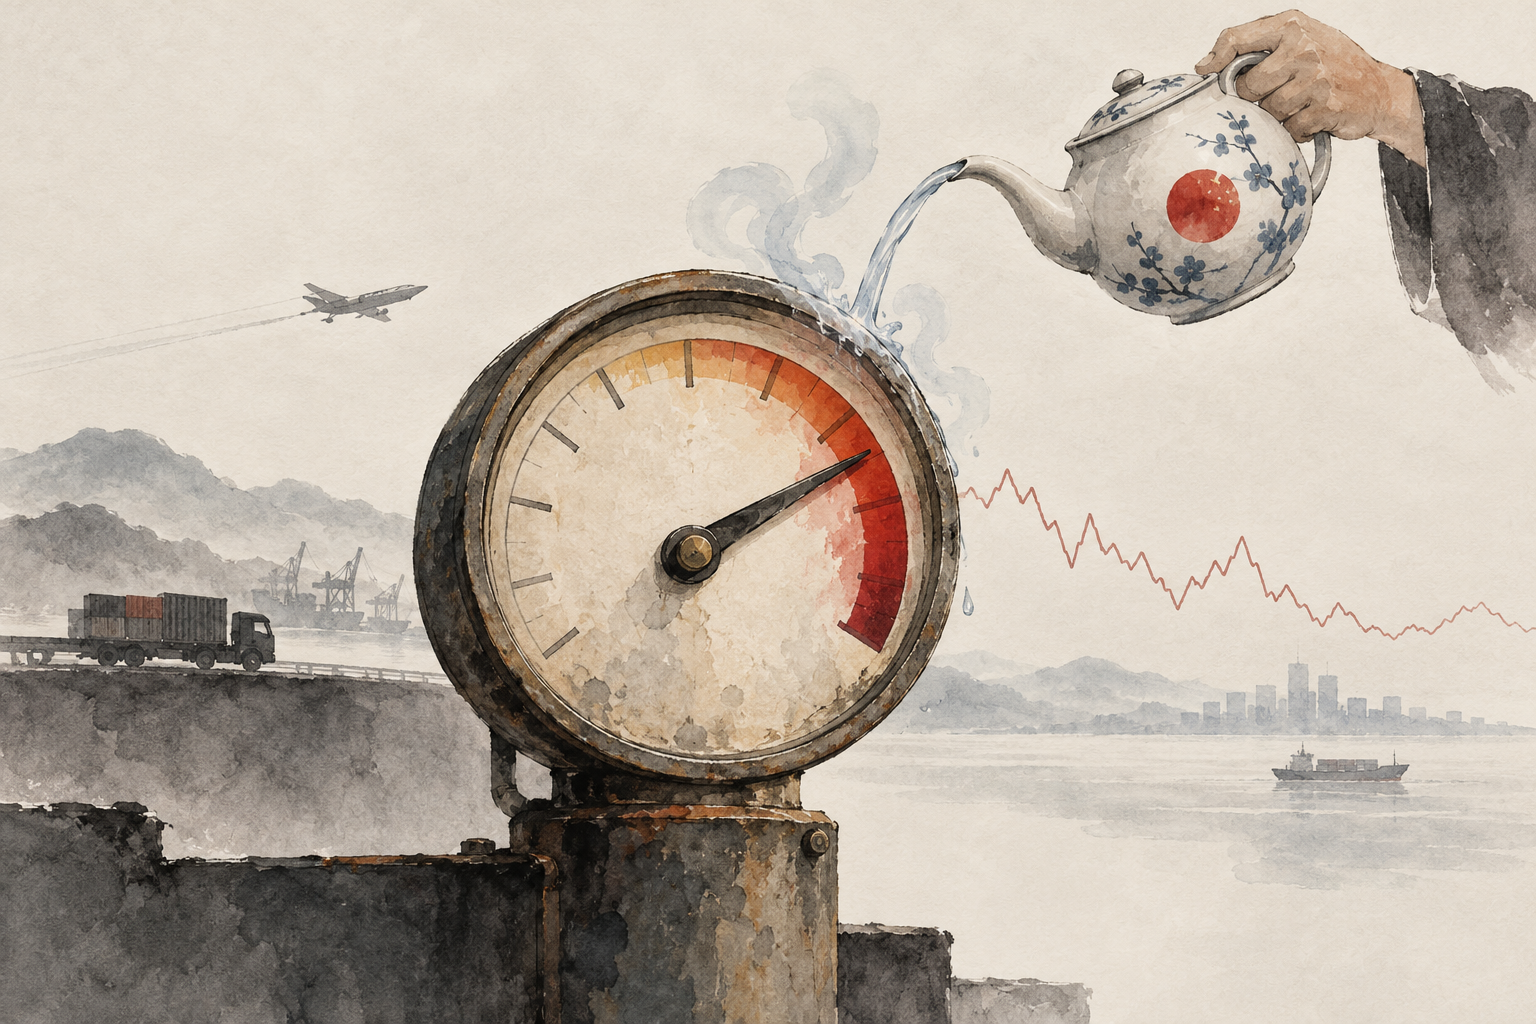
China has approved about 3.7 million metric tons of October diesel, gasoline and jet-fuel exports after a brief halt.
Cracks elevated
EIA data showed a Gulf Coast 3:2:1 crack spread of $57.22 a barrel, underscoring refined-product tightness.
Airline squeeze
S&P Global Market Intelligence data showed major U.S. airline fuel expenses expected to rise 55% to 67% year over year.
China’s expected return to refined-fuel exports in October offers timely relief to diesel, gasoline and jet-fuel markets. It does not change the macro story: energy remains the key variable for bond yields, inflation risk and transport-sector guidance.
Reuters reported that China is set to resume refined-product exports after a brief Golden Week halt, with October approvals for diesel, gasoline and jet fuel totaling about 3.7 million metric tons.1 On a rough barrel-equivalent basis, that is meaningful spot supply. It is enough to lean against acute product tightness in Asia and soften arbitrage pressure into other regions. But it is not enough to offset the broader loss of refining flexibility caused by Middle East disruption, Russian outages and depleted inventories.
The restart matters because markets are no longer trading only crude scarcity. They are trading a refining shock. The Dallas Fed estimates that global refinery capacity has been curtailed by as much as 6 million to 8 million barrels per day since late spring, or up to 10% of global refining. Outages and shipping constraints have widened crack spreads for diesel, gasoline and jet fuel beyond the move in crude itself.4 EIA’s latest daily price snapshot showed Brent at $126 a barrel on the October 7 close, New York Harbor low-sulfur diesel at $5.00 a gallon and the Gulf Coast 3:2:1 crack spread at $57.22 a barrel — a level consistent with product scarcity rather than a simple crude rally.5
China’s export approvals should provide the most direct relief in middle distillates and jet fuel, where constraints have been most visible. If the approved October volume moves smoothly, it may reduce panic buying, improve prompt availability and cool some regional freight and aviation-fuel premiums.
That matters for airlines and transport operators, because the marginal cost problem is already showing up in earnings expectations. Visible Alpha consensus data compiled by S&P Global Market Intelligence showed fuel expense for six major U.S. airlines forecast to rise 55% to 67% year over year in the third quarter, far outpacing expected revenue growth of 16% to 22%.10
In that context, incremental Chinese jet-fuel exports can help cap spot-market stress. They do not solve the margin squeeze on their own. Airlines still have to decide how much higher fuel cost can be passed through fares without damaging demand.
For diesel users — trucking, rail, mining, agriculture and marine logistics — the restart is similarly helpful but incomplete. Diesel is the product most closely tied to freight inflation and industrial activity. Additional Chinese cargoes can ease regional shortages, but the global market remains dependent on how fast damaged or constrained refining systems recover and whether shipping routes remain reliable.
The larger constraint is that product markets are entering October with thin buffers. The Dallas Fed argues that elevated fuel prices reflect “acute, multifaceted supply constraints” and warns that crack spreads may linger even after crude flows normalize, because damaged refineries, export restrictions and logistics bottlenecks are product-specific problems.4
That distinction matters. Crude can be available while diesel or jet fuel remains scarce in the wrong place.
The 3.7 million-ton approval also has to be measured against the scale of disruption. Even if the volume is roughly equivalent to close to one million barrels per day over a single month, it is a temporary flow decision, not a structural increase in global refining capacity. It can change the slope of the price spike. It is less likely to reset the level of fuel costs.
That is why refined products remain central to corporate guidance. Airlines can hedge, trim capacity or push fares higher, but jet fuel is still a large cash cost. Trucking companies can use fuel surcharges, but surcharges lag and can weaken volumes. Retailers and manufacturers can renegotiate logistics contracts, but transportation inflation ultimately feeds into working capital, inventory and pricing decisions.
The macro transmission is already visible. Reuters reported that rising oil prices and Middle East supply worries weighed on Treasuries before a strong 30-year auction helped yields rally, and noted that oil remained a major driver of Treasury yields by stoking inflation concerns.6 A separate Reuters market report said Brent jumped 4.2% to more than $104 a barrel on Middle East supply worries while the 10-year Treasury yield stood at 5.29%, near its highest level since 2002.7
China’s export restart may reduce the tail risk of an immediate product squeeze, but it does not remove energy from the rates equation. Bond investors are still likely to treat oil and refined fuels as live inflation inputs, especially when crack spreads are amplifying the pass-through from crude to wholesale diesel, gasoline and jet fuel.
The implication for commodities and transport readers is straightforward: the Chinese cargoes are a volatility cap, not a volatility cure. They can ease the tightest prompt-market conditions and reduce the risk of disorderly fuel procurement. But unless refinery availability improves, shipping risk falls and inventories rebuild, energy prices will remain the dominant swing factor for transport margins, inflation expectations and bond-yield volatility.
China’s October fuel-export restart is bearish at the margin for refined-product cracks and constructive for airlines and transport buyers seeking physical supply. But the relief is tactical. The strategic issue is still a world short of flexible refining capacity, just as geopolitical disruption is forcing markets to price not only barrels of crude, but barrels of usable diesel, gasoline and jet fuel.
Comments