Nvidia’s China Risk Shifts From Licensing Delays to Platform Displacement
Sovereign AI
AI infrastructure and models controlled by a country or domestic companies, often favored for security, policy and data-residency reasons.
Accelerator
A chip designed to speed up AI training or inference workloads, such as GPUs, NPUs or custom AI processors.
FP8 / FP4
Lower-precision number formats used in AI workloads to improve speed and efficiency, especially in large-scale inference and training.
Supernode
A tightly connected cluster design that links many accelerators with high-speed networking so they can act like a larger AI compute system.
Alibaba Cloud
other
Alibaba Unveils Roadmap on Full-Stack AI Strategy from Chips, Cloud Infrastructure, Models to Agents
Alibaba Group
other
Alibaba Group CEO Eddie Wu Shares Alibaba’s Strategic Full-Stack AI Roadmap at the 2026 Apsara Conference
Reuters via Investing.com
news
Alibaba deepens AI push with new chip, bigger model; shares jump 5%
V900 roadmap
Alibaba says its Zhenwu V900 delivers 3x the prior M890 performance and is scheduled for Q1 2027 commercial release.
20GW target
Alibaba Cloud aims to operate more than 20GW of global data-center capacity by 2032 to support AI demand.
Huawei demand
Huawei is reportedly keeping next-generation Ascend AI accelerators mainly inside China because domestic demand exceeds supply.
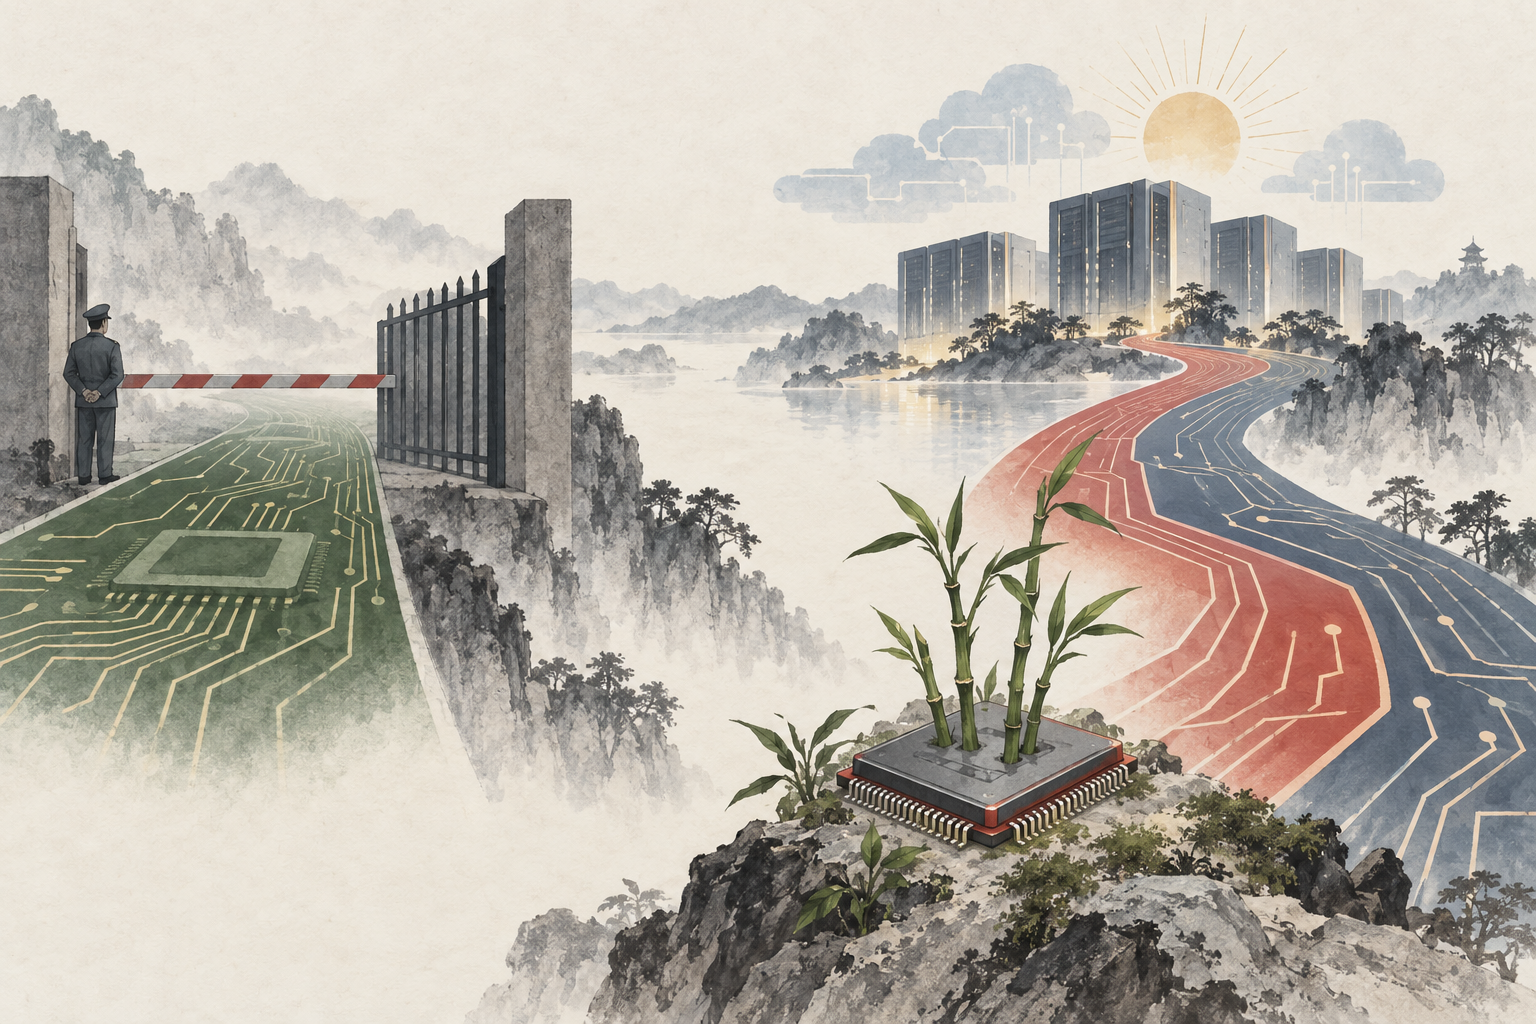
Nvidia’s China upside is becoming less a binary bet on U.S. licensing relief and more a race against Chinese AI platforms using the export-control window to harden domestic supply chains. Alibaba’s Sept. 22 Apsara announcements — the new Zhenwu V900 accelerator, Qwen 4 in training, a Qwen 4.5/Qwen 5 roadmap targeting 5 trillion to 10 trillion parameters, and a plan for Alibaba Cloud-operated capacity to surpass 20GW by 2032 — point to a China AI stack trying to move from workaround to replacement.1
For NVDA investors, the implication is sharper than another missed quarter of China data-center sales. Export curbs may be permanently changing buyer behavior. Chinese cloud providers, state-linked enterprises and sovereign AI projects now have both political pressure and increasingly credible local options from Alibaba, Huawei and others. Even if Washington later reopens some channel for compliant Nvidia chips, the addressable opportunity may be smaller, more price-sensitive and more contested than the pre-curb market.
Alibaba did not unveil the V900 as a standalone component. It framed the chip as part of a full-stack strategy spanning proprietary silicon, AI networking, storage, Qwen foundation models, enterprise agents and cloud infrastructure.1 Eddie Wu’s keynote made the strategic logic explicit: Alibaba is building around the three pillars of “AI models, AI chips, and the AI cloud,” arguing that infrastructure is the foundation for delivering machine intelligence at scale.2
That framing matters because Nvidia’s moat has historically been broader than raw GPU performance. CUDA, networking, systems integration and developer adoption have turned Nvidia GPUs into a platform. Alibaba is trying to answer with a vertically integrated domestic stack: T-Head chips, supernodes, Alibaba Cloud, Qwen models and enterprise agent services.
In other words, the competitive question is not whether the V900 beats the latest Nvidia part in every benchmark. The more relevant question is whether Alibaba can offer a good-enough, China-local platform for workloads that Chinese customers increasingly prefer — or are encouraged — to keep off foreign hardware.
The V900 claims are meaningful but still vendor-reported. Alibaba says the chip delivers three times the performance of the prior Zhenwu M890, includes 216GB of GPU memory, supports FP8 and FP4, and offers 1,200GB/s of inter-chip bandwidth, with mass production and commercial release scheduled for Q1 2027.1 Wu also called the V900 “the most powerful AI chip in China today” and said a single V900 cluster could scale to 500,000 cards.2
TechRadar noted the missing details — no FLOPS figure, process node, foundry, power rating or full performance disclosure — which means investors should treat the specification set as directionally important rather than independently benchmarked.11
Still, China’s buyers do not need perfect parity if the alternative is uncertain access to Nvidia. They need predictable supply, acceptable software migration paths, sovereign control and pricing that works at scale. Alibaba’s roadmap is designed around those needs.
The chip announcement was paired with a much larger model roadmap. Alibaba said Qwen 4 is already in training and that future Qwen 4.5 and Qwen 5 models are expected to scale to 5 trillion to 10 trillion parameters.1 Reuters reported that the model roadmap, the V900 launch and Alibaba’s broader data-center buildout come as Chinese tech companies race to develop domestic alternatives to Nvidia processors amid tightening U.S. export curbs.3
This matters because the local accelerator market is not waiting passively for outside demand. Alibaba’s own model roadmap can generate captive or quasi-captive demand for its silicon and cloud capacity.
Qwen technical work also points beyond chatbot inference toward agentic and multimodal workloads. The Qwen3.8-Omni paper describes native omni-modal agents, a 1M-token context capability and long-horizon agentic tasks, while the Qwen-Audio-Agent report addresses full-duplex voice interaction and asynchronous task execution.1314 Those applications increase sustained inference demand, not just episodic training demand.
Alibaba Cloud’s Sept. 23 release on global infrastructure and AI services broadens the competitive frame further. The company is not simply saying it can build a chip; it is packaging compute, cloud regions, model services and enterprise tools into an adoption funnel.12
That is where Nvidia’s China risk becomes more structural: once workloads are built and optimized around Alibaba Cloud or Huawei Ascend ecosystems, future licensing relief may not automatically bring them back to Nvidia.
Huawei’s recent chip push underscores the same trend from another direction. Tom’s Hardware reported that Huawei’s next-generation Ascend 900-series accelerators will be offered mainly inside China because domestic demand exceeds capacity, citing Huawei’s view that it lacks enough supply even for the Chinese market.7 That is a strong signal that substitution is not merely a policy aspiration; it is translating into demand that can absorb scarce domestic output.
Sell-side coverage of Huawei Connect also points to a platform-level race. UOB Kay Hian highlighted Huawei’s Ascend 960 schedule pull-in, Atlas 960E SuperPoD, NPO interconnect and architecture aimed at 10-trillion-parameter models.8 The target is similar to Alibaba’s: build not only chips, but clusters and interconnects capable of supporting frontier-scale Chinese models.
This creates a reinforcing loop. Export restrictions limit the supply of top Nvidia chips. Scarcity pushes Chinese buyers to test local silicon. Local deployments improve software stacks, operational expertise and customer confidence. That, in turn, supports more domestic chip investment and reduces the perceived risk of moving away from Nvidia. The longer curbs remain binding, the more this loop compounds.
Nvidia still has the superior global platform, the deepest software ecosystem and unmatched relevance in frontier AI infrastructure outside China. That is why China remains an upside scenario rather than a base-case necessity for many investors. The Motley Fool noted that Nvidia’s $108 billion fiscal third-quarter revenue forecast assumed no China data-center compute revenue, while customers headquartered in China made up about 8% of revenue in the prior quarter, with little of that from data-center compute.9
That setup gives Nvidia a clean near-term narrative: any licensing relief could be incremental. But the longer-term investor question is whether incremental access would restore prior economics. AP’s coverage captured the competitive shift: Chinese-designed chips are gaining ground while Nvidia remains blocked from selling some of its most powerful AI chips to China.4 Reuters similarly tied Alibaba’s launch to Chinese efforts to build Nvidia alternatives.3
The risk is that a reopened China market becomes a mixed market. Nvidia could regain some high-end or compliant-chip demand, particularly where CUDA dependence remains heavy. But sovereign workloads, public-sector AI, state-owned enterprise deployments and cloud-native Chinese model platforms may increasingly default to domestic accelerators.
In that scenario, U.S. licensing relief would not unwind the substitution already underway. It would merely allow Nvidia to compete for the portion of demand that has not yet been replatformed.
The first watch item is execution. Alibaba’s V900 is scheduled for Q1 2027 commercial release, so production volumes, yield, customer adoption and real-world training and inference benchmarks matter more than launch claims.1 If Alibaba can show large-scale deployment across its cloud and external customers, the V900 becomes a platform event. If it slips or underperforms, Nvidia’s China optionality improves.
The second watch item is software gravity. Investors should monitor whether Qwen workloads, agent platforms and enterprise AI services are optimized primarily for Alibaba hardware and cloud primitives. Once model-serving costs, tooling and developer workflows are tuned to local accelerators, switching back to Nvidia becomes less automatic.
The third watch item is Huawei supply. If Huawei is capacity-constrained because Chinese demand is absorbing Ascend output, that supports the view that China is building a domestic compute market large enough to stand on its own.7 If Huawei and Alibaba both scale, Nvidia faces not one substitute but a portfolio of national champions competing across cloud, telecom, government and enterprise channels.
Bottom line: the bull case for Nvidia does not require China. But the China upside case now deserves a lower probability and a more conservative multiple. Alibaba’s Sept. 22 roadmap and Huawei’s parallel Ascend push suggest export controls are no longer just delaying Nvidia revenue. They are training Chinese customers, developers and cloud providers to live without it.


Comments