Golden Week’s travel boom may not deliver a profit boom
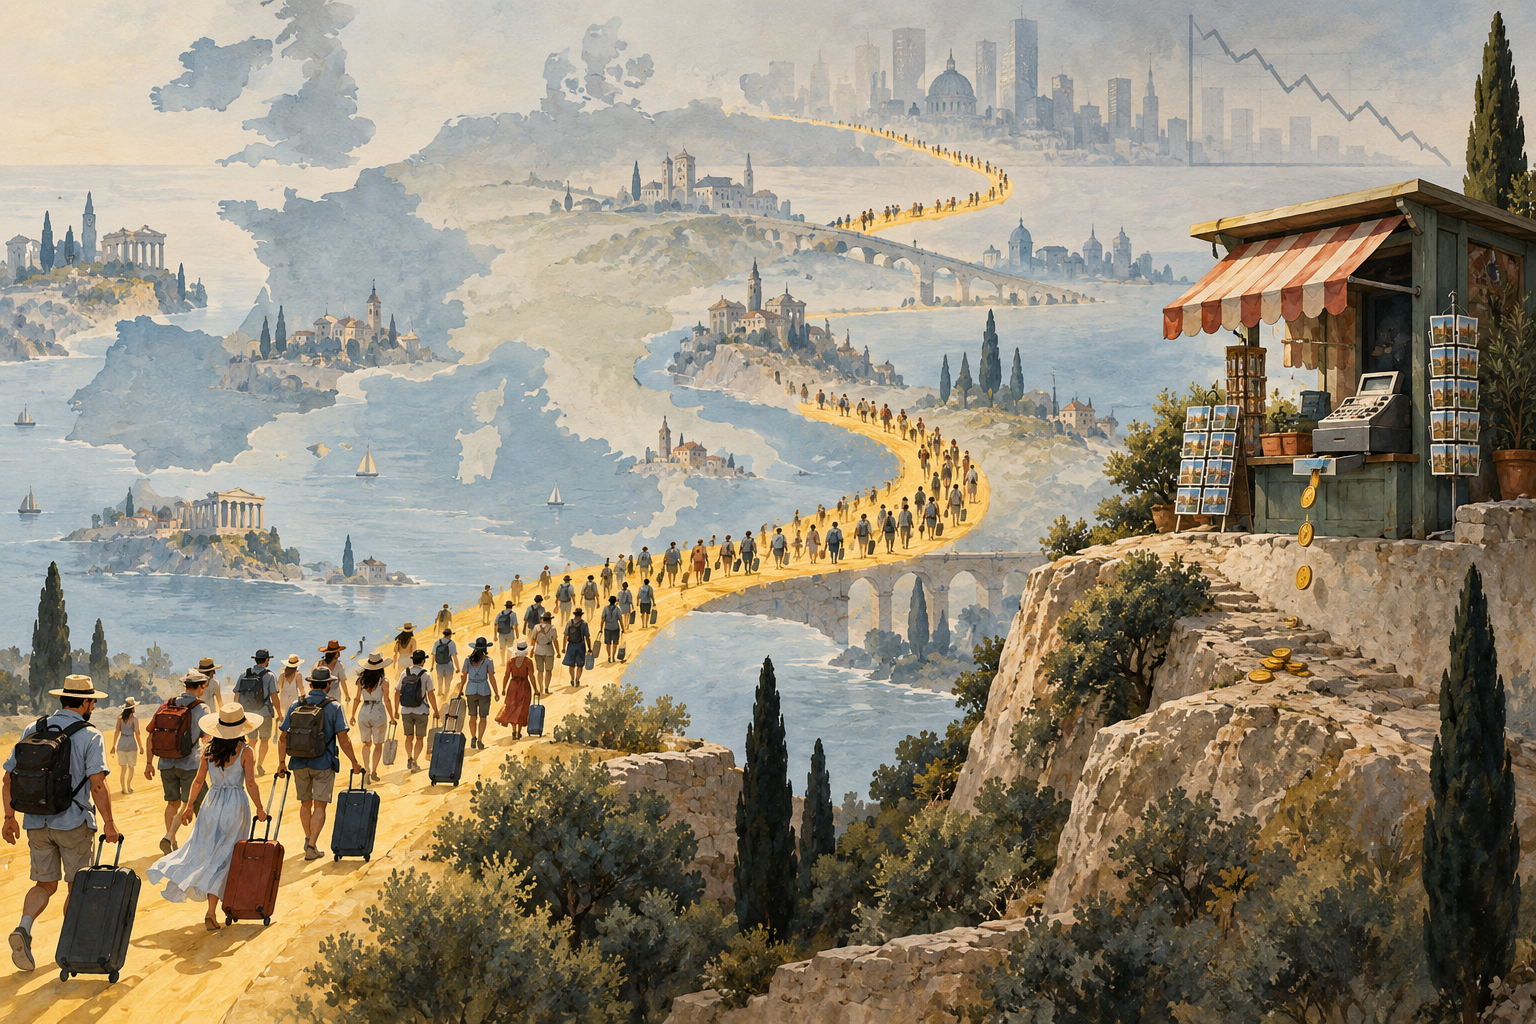
Golden Week
A major Chinese holiday period around National Day that typically produces one of the year’s biggest waves of domestic travel and consumption.
Mobility versus monetisation
The difference between people travelling in large numbers and companies actually converting that traffic into higher revenue, pricing power and profit.
Southbound Stock Connect
A trading link that allows mainland Chinese investors to buy selected Hong Kong-listed stocks; it is typically suspended when mainland markets are closed.
Per-trip spending
The amount consumers spend on each journey, including transport, hotels, dining, shopping and entertainment.
City News Service
news
Hong Kong Stocks Slump, Chinese Mainland Markets Pause for Weeklong Holiday
Global Times
news
China’s travel during National Day holidays stays elevated on third day as short-haul trips gain momentum
Global Times
news
Travel demand stays high across China as multiple scenic spots impose visitor limits amid ongoing National Day holidays
Stocks slide
Hong Kong’s Hang Seng Index fell 2.6% while mainland markets were closed for the National Day holiday.
Mass travel
China’s Ministry of Transport forecast 2.13 billion cross-regional trips over the seven-day Golden Week holiday.
Spending split
Heavy traffic is not yet proving a broad rebound in per-trip spending, leaving tourism profitability and luxury demand uncertain.
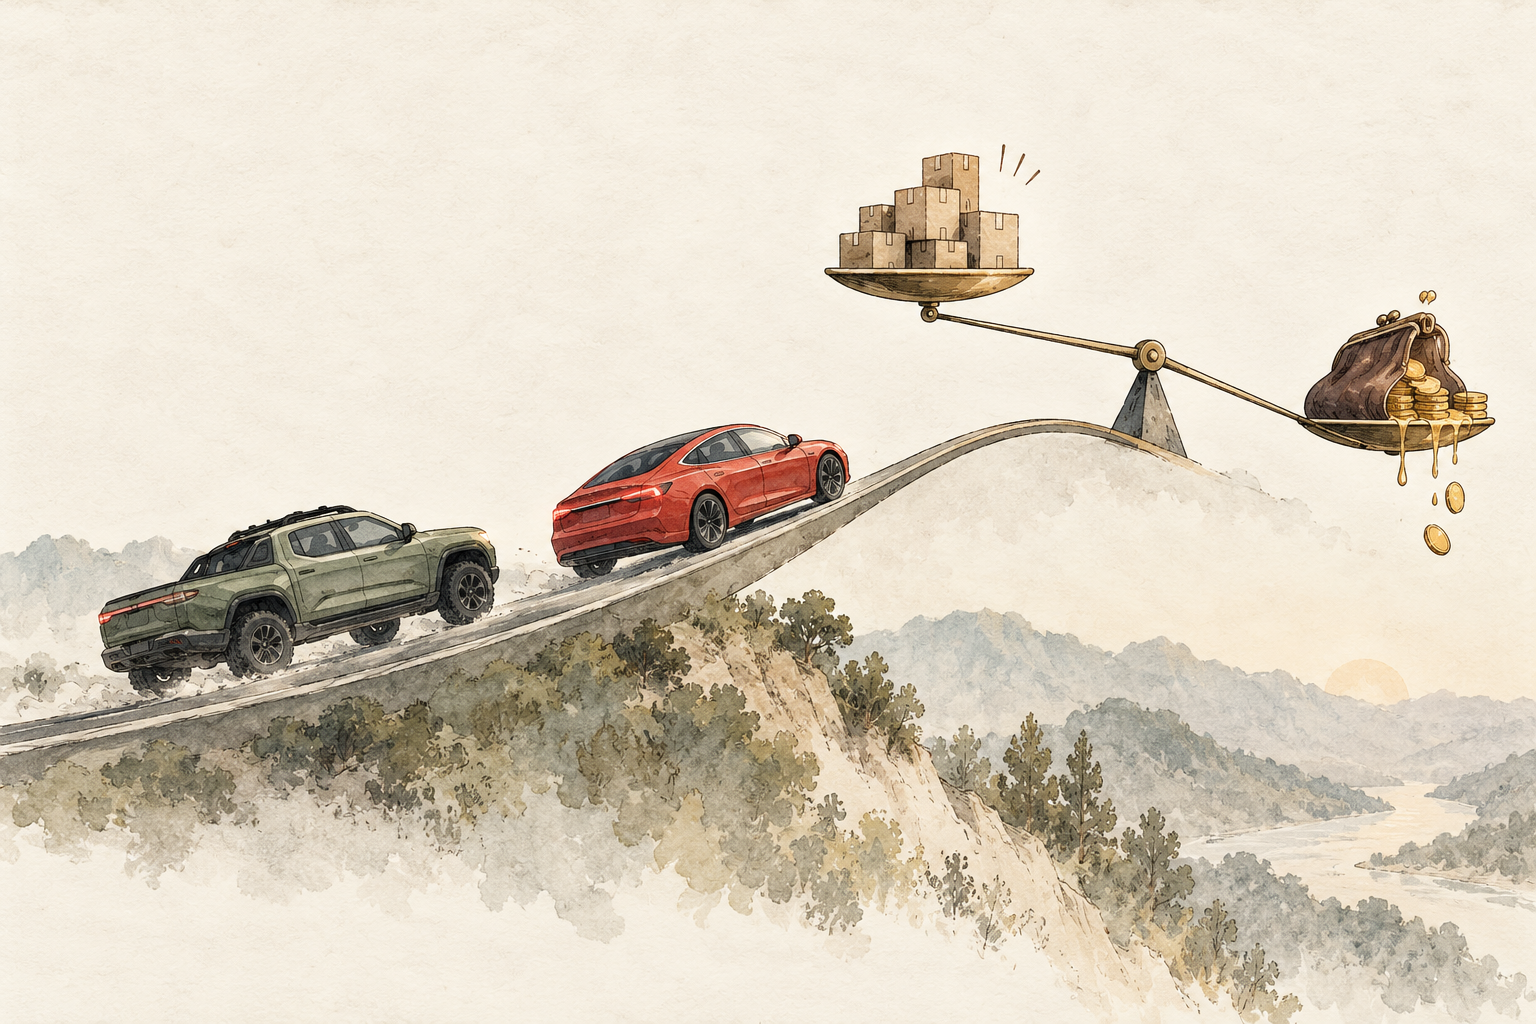
China’s Golden Week is confirming that households are still willing to travel, but not necessarily that they are willing to spend freely.
For global consumer and Asia-market investors, the key read-through is a widening gap between mobility and monetisation. Trains, airports, border checkpoints and scenic areas are busy. Yet weaker spending intensity and bargain-seeking behaviour could cap the earnings upside for tourism, retail, luxury, Macau gaming and China-linked equities.
The market has already started to price that risk. Hong Kong stocks fell sharply while mainland China markets were closed for the weeklong National Day holiday, with the Hang Seng Index down 2.6% and weakness spreading across technology, financials and China-linked listings.1 A separate market roundup noted the index slipping below 24,000, with Southbound Stock Connect suspended during the holiday and early retail and dining signals mixed.11
That matters because Hong Kong is one of the few live trading venues for investors trying to interpret China’s holiday demand in real time.
The volume story is clearly positive. China’s Ministry of Transport forecast 2.13 billion cross-regional trips over the seven-day holiday, making Golden Week one of the largest annual tests of domestic consumer activity.4 State media reports also pointed to elevated third-day travel demand, strong railway passenger expectations and rising momentum in short-haul trips.2
Other data points reinforce the same picture. Xinhua, citing travel platforms and China Railway, reported longer itineraries, multi-city stays and record railway passenger trips, suggesting households are using the extended break to travel more widely rather than staying close to home.5 Scenic spots have been busy enough that some imposed visitor limits, while transport operators added capacity and duty-free shopping showed growth in selected channels.3 Photo-led reporting from tourist and cultural sites across the country also showed heavy foot traffic during the early holiday period.6
That makes this Golden Week a poor proxy for whether Chinese consumers are leaving home. They are. The more important question is whether travel frequency is translating into pricing power, higher basket sizes and operating leverage.
The investor risk is that Golden Week delivers strong headline traffic but only modest revenue quality. Short-haul trips appear to be gaining momentum, which can support volumes but often brings lower per-trip spending than long-haul travel, premium hotel stays or outbound luxury shopping.2
Reports of visitor limits and added transport capacity indicate high utilisation across the tourism system. They do not, by themselves, prove that merchants, hotels or travel platforms are capturing materially better margins.3
Hong Kong’s early holiday numbers illustrate the split. Local reports said roughly 500,000 mainland visitors entered Hong Kong over the first two days of Golden Week, with retail and catering commentary pointing to busy tourist districts.8 Hong Kong’s culture, sports and tourism secretary also said first-day mainland visitor volumes exceeded both last year and the 2018 peak, while noting that expensive airfares could weigh on short-haul visitor demand from Southeast Asia.9 Official Hong Kong Immigration Department passenger-traffic data provide a way to verify daily inbound and outbound flows by control point and visitor category as the week progresses.10
For investors, the distinction is important. Strong arrivals may help restaurants, transit operators, convenience retail and mass-market attractions. But luxury groups, premium hotels, airlines and casino operators need higher spend per visitor, not just more visitors walking through the door.
The immediate read-through for global luxury is cautious. Golden Week can lift store traffic in Hong Kong, Macau, Hainan and major mainland shopping districts. But cost-conscious travel behaviour would be consistent with a consumer prioritising experiences, discounts and shorter itineraries over discretionary big-ticket purchases.
Duty-free growth is a supportive sign, but it is not enough to conclude that the high-end consumer has broadly reaccelerated.3
Macau gaming faces a similar interpretation problem. More mainland travel and stronger regional mobility should support visitation, but casino earnings are most sensitive to mass-market table drop, hotel rates, retail conversion and premium-player activity. If Golden Week traffic is skewed toward shorter, more budget-aware trips, the volume uplift may not translate into the same profit expansion investors saw in stronger consumption cycles.
Travel platforms, online agencies and rail-linked names may be better positioned to benefit from the mobility side of the story. Even there, demand quality matters. Discounted packages, shorter booking windows and lower-priced domestic routes can support gross bookings while pressuring take rates or average order value.
The selloff in Hong Kong equities is not just a local market move. It reflects a broader concern that investors had already priced in a cleaner China consumption recovery than the holiday data may justify. With mainland exchanges closed, Hong Kong-listed Chinese technology, financial, property, travel and consumer names became the main instruments for expressing caution.1
The pressure also has global implications. European luxury houses, Asia airlines, hotel operators, travel retailers, Macau concessionaires and multinational consumer brands all depend, to varying degrees, on Chinese discretionary spending. A Golden Week defined by crowded trains but careful wallets would support revenues tied to traffic, while challenging earnings narratives that depend on higher-margin consumption.
The most important data will come after the holiday, when official and company-level figures show whether traffic converted into revenue. Investors should focus on per-capita tourism spending, hotel occupancy versus room rates, Macau gross gaming revenue trends, Hong Kong retail sales commentary, duty-free basket size, restaurant spend and online travel agency order values.
For now, the message is mixed but investable: China’s consumer is mobile, not necessarily exuberant. That distinction may decide whether Golden Week becomes a catalyst for consumer cyclicals or another reminder that China’s recovery remains volume-heavy and margin-light.
Comments