Wetherspoon rally tests whether sales momentum can outrun pub cost inflation
Like-for-like sales
Sales growth from comparable sites, excluding the effect of openings, closures or major changes to the estate.
Operating leverage
The extent to which extra revenue converts into profit after fixed costs are covered.
Pre-tax profit before exceptional items
A profit measure that excludes one-off gains or charges, often used to assess underlying trading performance.
Business rates
A property-based tax paid by occupiers of commercial premises in the UK, including pubs and restaurants.
Revenue rises
Wetherspoon revenue increased 5.2% to £2.24bn, but adjusted pre-tax profit fell 28% to £58.6m.
Sales accelerate
Like-for-like sales rose 8.6% in the nine weeks to 27 September, helped by warm weather and outdoor seating.
Margin squeeze
Operating margin before one-offs narrowed to 5.37% from 6.88% as wage, repair and rates costs rose.
J D Wetherspoon’s latest results give UK equity investors a clear test of the leisure sector’s post-inflation model: customers are still turning up, but profit conversion has not returned to pre-pandemic form.
Revenue rose 5.2% to £2.24bn in the year to 26 July and like-for-like sales increased 4.2%. Yet pre-tax profit before exceptional items fell 28% to £58.6m, as labour, repairs, energy and business rates outpaced turnover growth.1
The market focused on the forward-looking line. Wetherspoon said like-for-like sales rose 8.6% in the nine weeks to 27 September, helped by warm weather and investment in beer gardens and outdoor seating.1 Alliance News reported that the shares surged 12% in the FTSE 250 after the update, while Small Cap News noted a 5% rise in early trading.51
That relief rally is understandable. The company is guiding to profit in line with market forecasts, and Proactive Investors reported consensus pre-tax profit before one-offs at about £74m for the current financial year, implying a recovery from £58.6m.3
The question is whether that reflects operating leverage, or simply weather leverage.
The bull case is straightforward. Wetherspoon has scale, a value-led price position, strong cash generation and a long record of taking share from weaker pub operators.
It also continues to outperform the wider industry. Proactive reported that August like-for-like sales rose 7.7%, compared with 0.8% for the NIQ RSM Hospitality Business Tracker, and that Wetherspoon had beaten that tracker for 48 consecutive months.3
That relative performance matters. In a squeezed consumer environment, Wetherspoon’s low-price offer can act as a volume magnet. If fixed costs are already covered, incremental pints, meals and coffees should drop through to profit at attractive rates.
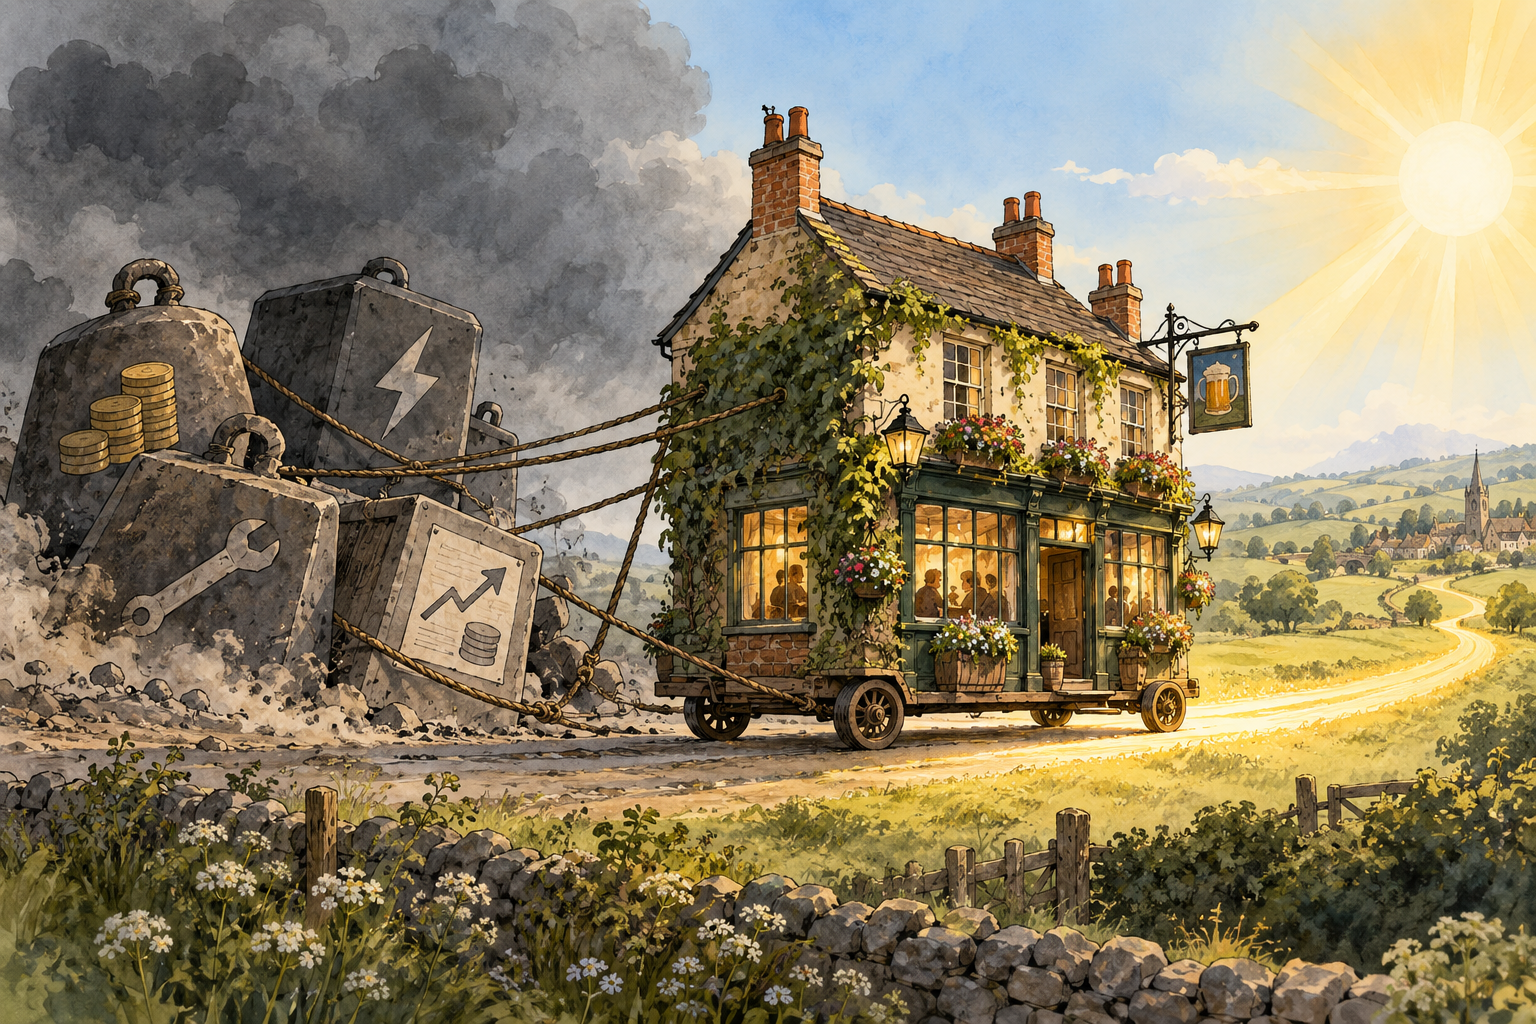
But the FY26 numbers show that the mechanism remains impaired. Costs rose slightly faster than sales. Proactive reported £46m of additional wage cost, £31m of extra repairs and £9m more business rates. Operating profit before one-offs fell 18% to £120.2m, while operating margin narrowed to 5.37% from 6.88%.3
Small Cap News similarly described the profit fall as cost-driven rather than demand-driven, with wages, repairs and rates dragging margins lower.1
That is the key read-across for UK leisure equities. Demand resilience is necessary, but not sufficient. If the cost base resets higher each year, revenue growth has to be materially stronger just to keep margins flat.
Management appears cautious about extrapolating the recent acceleration. Proactive reported that chairman Tim Martin attributed part of the strong start to exceptional weather and warned that conditions would inevitably normalise.3
The company has made itself more weather-sensitive in a positive way by adding outdoor space. Hot spells that might once have pulled consumers toward parks and beaches can now support beer-garden trading.
That is good estate management. But investors should separate structural share gains from seasonal uplift. The nine-week 8.6% like-for-like figure is impressive, yet it covers late summer trading. The tougher test is whether sales momentum persists through colder months, when outdoor seating contributes less and consumers face winter energy bills, rent resets and tax uncertainty.
The next scheduled trading update on 4 November therefore carries unusual weight.3 A continuation of high-single-digit like-for-like growth would strengthen the case that Wetherspoon is achieving genuine volume-led operating leverage. A slowdown back toward the full-year 4.2% rate would make the FY27 profit recovery look more dependent on cost control, pricing and political relief.
Wetherspoon’s challenge is that its competitive edge is also a constraint. The group has historically used value pricing to pull customers away from rivals, a proposition that is especially useful when household budgets are tight. But passing through every increase in payroll, energy, property and rates would weaken the same value credentials that are driving footfall.
That makes margin recovery a balancing act. Raise prices too little, and profit growth remains hostage to cost inflation. Raise prices too much, and the company risks losing the traffic advantage that has helped it outperform the market.
The dividend and buyback suggest management confidence. Proactive reported that the total dividend was held at 12p and that Wetherspoon spent £46m buying back 6.2% of its shares, while free cash flow nearly doubled to £100.1m.3
For shareholders, that capital return softens the near-term earnings disappointment. It also signals that the board views the cost squeeze as manageable rather than existential.
Still, the margin data argue against assuming a rapid return to old economics. A business can be operationally stronger than peers while still earning structurally lower margins than it did before wage and tax inflation reset the industry cost base.
The political backdrop is material because business rates and employment costs are not peripheral expenses for pub operators. Small Cap News reported that Martin used the results to renew criticism of government policy and again called for VAT parity between hospitality and supermarkets.1 Proactive also noted Martin’s argument that pubs and restaurants hand around 40% of takings to the Treasury through various taxes.3
There may be some relief ahead. LBC reported that the Prime Minister had announced a 20% business-rates cut for pubs, clubs and live music venues from next April, although broader business groups still want more stability and relief from rising costs.8
Separately, iTechGuides noted that the Autumn Budget is scheduled for Wednesday 28 October 2026 and cautioned that future tax, rates or relief measures should be treated as unknown until formally announced.10
For investors, that means Wetherspoon is partly a policy-sensitive equity. Any confirmed easing in rates would help, but the market should be wary of capitalising political promises before the details are known. Eligibility, timing and interaction with other tax measures will determine the real cash benefit.
The rally was not irrational. Wetherspoon is growing sales, winning share, generating cash and indicating that current-year profit should recover toward market expectations. In a UK consumer sector where many companies would envy high-single-digit current trading, the share-price relief reflects genuine demand strength.
But the results do not yet prove a clean operating-leverage story. FY26 showed the opposite: turnover rose, but adjusted pre-tax profit fell sharply because costs moved faster. Until Wetherspoon demonstrates that stronger sales can expand margins through a full trading cycle, the shares remain a test case rather than a settled recovery.
The key indicators from here are simple: whether like-for-like sales stay above cost inflation after the summer period; whether wage, repair, energy and rates growth moderates; whether the 5.37% operating margin begins to rebuild; and whether any Budget or rates relief reaches the profit and loss account without being competed away through lower prices.
For UK equity investors, Wetherspoon’s results say the consumer is not broken. They do not yet say the pub profit model is fixed.
Comments