TotalEnergies Turns African Midstream Cash Flows Into $1.8 Billion of Balance-Sheet Capital
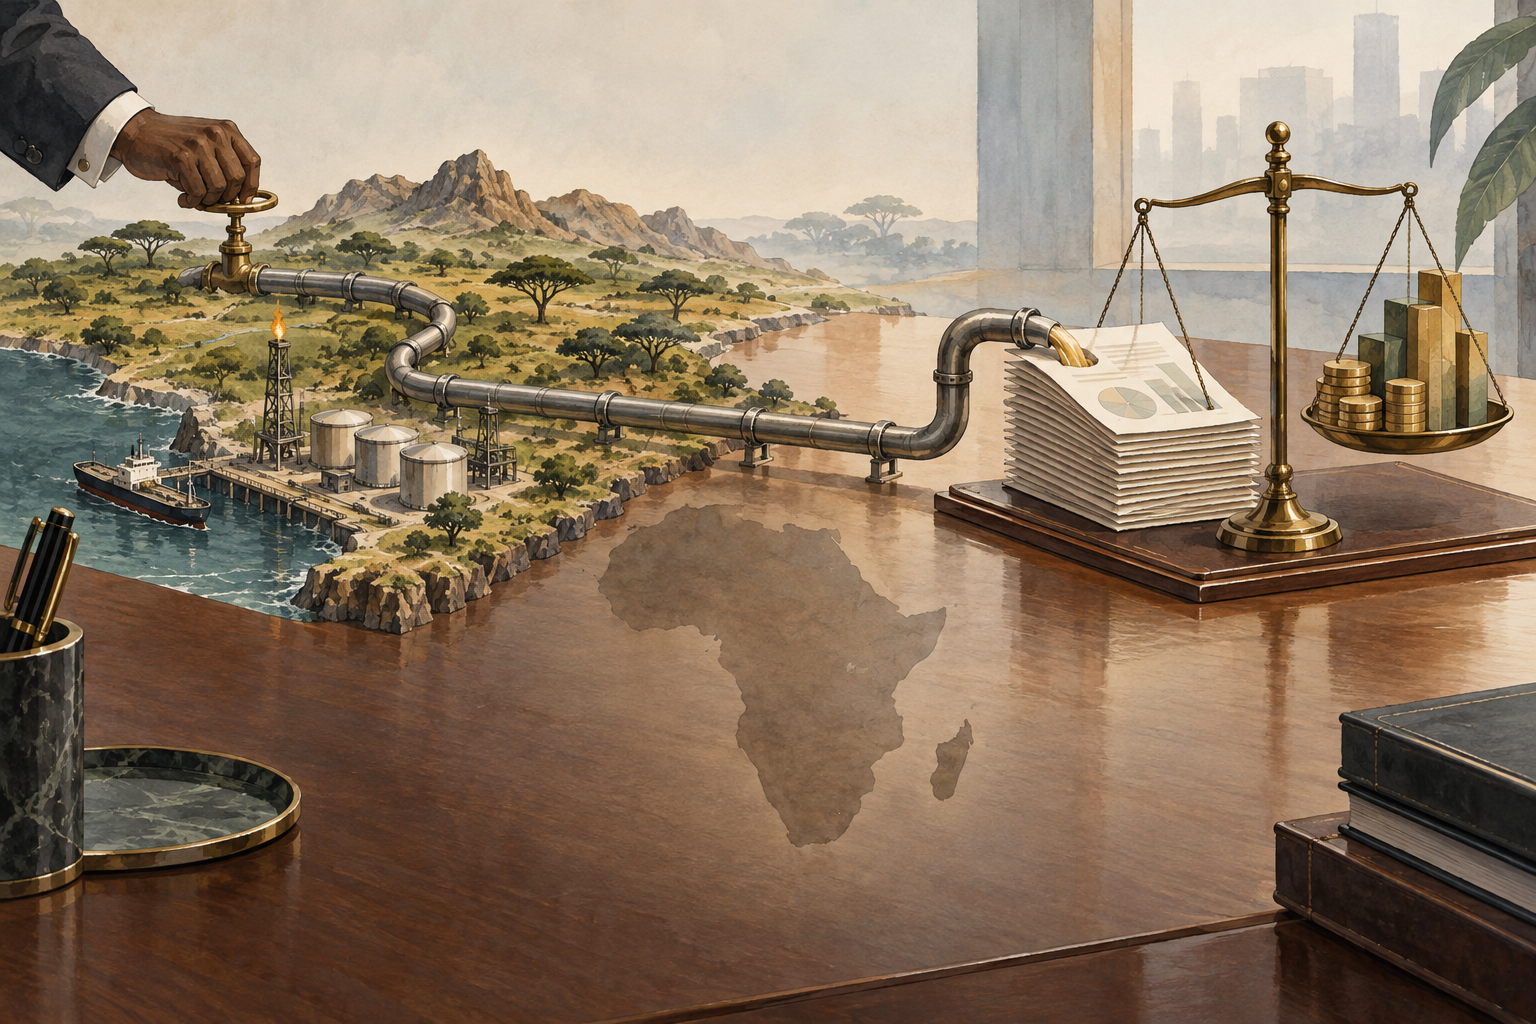
Midstream assets
Energy infrastructure such as pipelines, processing plants, storage and export systems that move hydrocarbons from production sites to markets.
Throughput-based tariff
A fee paid according to the volume of oil, gas or related products moving through an infrastructure asset.
Sale-and-leaseback-style monetisation
A financing structure in which a company raises cash from an asset while continuing to use it through contractual payments.
Capital recycling
The process of selling or monetising mature assets and redeploying the proceeds into debt reduction, shareholder returns or new investments.
TotalEnergies
other
TotalEnergies Signs an Agreement with GIP on African Energy Infrastructure Assets
TotalEnergies
other
TotalEnergies signe un accord avec GIP portant sur des actifs d’infrastructures énergétiques en Afrique
Rigzone
news
TotalEnergies Secures $1.8B in Capital from GIP for African Assets
$1.8B capital
GIP will contribute $1.8 billion under a partnership covering TotalEnergies’ African oil and gas infrastructure assets.
Tariff model
TotalEnergies will retain operational access through throughput-based tariffs over a term of up to 15 years.
Repeatable template
The structure could become a model for majors seeking to monetise midstream assets while avoiding outright exits.
TotalEnergies’ $1.8 billion agreement with Global Infrastructure Partners is best read as a financing transaction built around operating infrastructure. The French major is converting long-lived African midstream assets into upfront capital while preserving access to the systems through throughput-based tariffs for as long as 15 years.1
The structure matters beyond TotalEnergies. In a higher-rate environment, integrated energy companies are under pressure to fund dividends, buybacks, transition investments and upstream growth without letting leverage rise. The GIP deal shows one route: recycle capital from stable infrastructure cash flows into corporate flexibility, while shifting part of the ownership economics to investors that value contracted infrastructure differently from public oil-equity markets.
The transaction also provides a fresh valuation signal for African midstream infrastructure. TotalEnergies has not disclosed the individual assets, countries or tariff formula. But the $1.8 billion capital contribution from a BlackRock infrastructure platform suggests institutional demand remains deep for energy infrastructure with predictable volumes, contractual protections and strategic links to upstream production.56
TotalEnergies said on 18 September that it had signed an agreement with GIP, part of BlackRock, covering African energy infrastructure assets. Under the arrangement, GIP will make a $1.8 billion capital contribution and receive remuneration through throughput-based tariffs over a term of up to 15 years.1
The French-language company release framed the deal as a way to crystallise value from TotalEnergies’ African midstream infrastructure portfolio. That reinforces the point that this is not a retreat from the region, but a monetisation of assets already embedded in the group’s operating system.2
For TotalEnergies, the key distinction is control of operational exposure. A conventional disposal would reduce capital employed, but it could also weaken integration between upstream fields and export or processing infrastructure. A tariff-based partnership lets the company keep using the assets while shifting part of the capital intensity to GIP.
In economic terms, the structure resembles a tolling or sale-and-leaseback-style model: TotalEnergies receives cash now and pays over time according to infrastructure usage.1112
That makes the deal a balance-sheet optimisation instrument first. It brings in $1.8 billion of upfront capital without forcing TotalEnergies to exit African oil and gas operations. It also creates a more explicit cost of infrastructure use, turning assets that may previously have been valued internally as part of an integrated upstream chain into separately priced midstream capacity.
The valuation logic is straightforward. Public oil majors are typically priced on commodity exposure, reserve life, capital discipline and shareholder distributions. Infrastructure funds, by contrast, often underwrite contracted or quasi-contracted cash flows, long-duration asset lives and inflation-linked or volume-linked tariff structures.
The same pipeline, processing or export system can therefore command different valuations depending on whether it sits inside an integrated oil company or an infrastructure vehicle.
GIP’s participation signals that African midstream assets can still attract large-scale institutional capital when the risk is structured around usage, term and sponsor quality. Market reports confirmed that a BlackRock fund will invest $1.8 billion in TotalEnergies’ African oil and gas infrastructure portfolio, with remuneration linked to throughput-based tariffs.89
For infrastructure investors, the appeal is exposure to essential energy logistics rather than pure exploration or production risk.
The missing details remain important. Neither the primary announcement nor subsequent trade coverage identified the precise assets, countries, tariff escalators or volume commitments.613 That limits investors’ ability to infer an exact multiple for African midstream infrastructure.
Still, the transaction establishes a benchmark: contracted use of hydrocarbon infrastructure in Africa can support billion-dollar capital commitments from global infrastructure capital, even as broader financing costs remain elevated.
The deal is likely to be studied by other majors because it addresses a common problem: how to fund capital-intensive portfolios when debt is more expensive and equity markets reward cash returns.
Energy groups with integrated upstream and midstream systems often own infrastructure that is critical but not always fully reflected in their share prices. Separating the infrastructure economics can release capital without selling production assets.
TotalEnergies has used similar logic before. Investor-facing coverage compared the new African infrastructure agreement with TotalEnergies’ earlier 2021 GIP-linked Gladstone LNG tolling-style arrangement, suggesting this is part of a repeatable financing toolkit rather than a one-off transaction.10
The principle is the same: monetise infrastructure value, retain commercial access and redeploy proceeds toward corporate priorities.
For peers, the model could be especially relevant where assets have stable throughput, long remaining life and limited need for operational control by the balance-sheet owner. LNG terminals, pipelines, storage systems, export facilities and processing assets are natural candidates.
The structure is less compelling where volumes are uncertain, assets are politically sensitive, or tariff arrangements would create future cost leakage that offsets the upfront proceeds.
For global energy investors, the transaction supports the view that majors can still unlock value from mature infrastructure portfolios without outright divestments. It may modestly improve TotalEnergies’ capital flexibility. Its broader significance, however, lies in price discovery: a sophisticated infrastructure buyer has assigned material value to African midstream cash flows at a time when capital is selective.
For infrastructure investors, the deal reinforces energy midstream’s role as a bridge asset class. It is not free of commodity, country or counterparty risk, but it can be structured around tariffs, volumes and long-term industrial necessity rather than direct oil-price exposure.
In that sense, TotalEnergies and GIP are dividing the risk stack. TotalEnergies keeps the upstream and operating interface; GIP takes exposure to infrastructure economics supported by throughput.
The main caveat is opacity. Without asset-level disclosure, investors cannot know whether the $1.8 billion reflects scarce, high-quality export infrastructure, a broader portfolio discount, or bespoke risk-sharing terms. That uncertainty prevents the transaction from serving as a clean valuation multiple for the whole African midstream market.
Even so, the strategic message is clear. In a world where capital has a higher price, ownership of stable infrastructure cash flows is negotiable. Access to those cash flows is what energy majors need operationally; full ownership is increasingly optional.


Comments